When the international debt mountain threatens to collapse

With public and private liabilities worldwide estimated at a staggering $353tn and with many gearing up to borrow more, all agree that there is a problem, but few agree on how to solve it

Al Majalla

When the international debt mountain threatens to collapse

There are moments when geography shapes economic destiny. At others, crises seize the initiative and quicken the pace of history. The pattern returns whenever energy security, supplies, trade, shipping routes, and growth come under pressure. For at least half a century, the Middle East has stood at the centre of that equation.

The October 1973 war and the first oil shock pushed the major industrial economies towards closer coordination, culminating in the creation of the Group of Seven (G7) in 1975. Born in the Cold War, the G7 gave leading capitalist powers a forum to confront economic disruption and protect the stability of energy supplies, but the global financial crisis of 2008-09 forced a wider reckoning.

Economic coordination could no longer be confined to the old industrial powers. The G20 was elevated to the leaders’ level, involving major emerging economies in global economic policymaking. China, India, Russia, Türkiye, Saudi Arabia, Mexico, and South Africa joined a forum that became the broadest mechanism for coordinating global economic policy.

Oil wealth was reshaping the system at the same time. The surpluses accumulated by oil-producing states, particularly in the Gulf, gave their sovereign wealth funds growing influence over global capital flows and investment. More members meant a bigger agenda. Debt, climate change, technology transfer, competition policy, fair trade, migration, and sustainable development all moved into view for the G20.

By 2026, it accounted for about 85% of global output and about two-thirds of the world’s population. Trade expanded, capital flowed more freely, and emerging economies surged. The global economy grew with them. World output doubled in the decade before the financial crisis, from about $31tn in 1999 to $62tn in 2008. Similarly, the years after World War II saw strong global growth, with emerging economies steadily becoming some of its principal engines.
Reuters
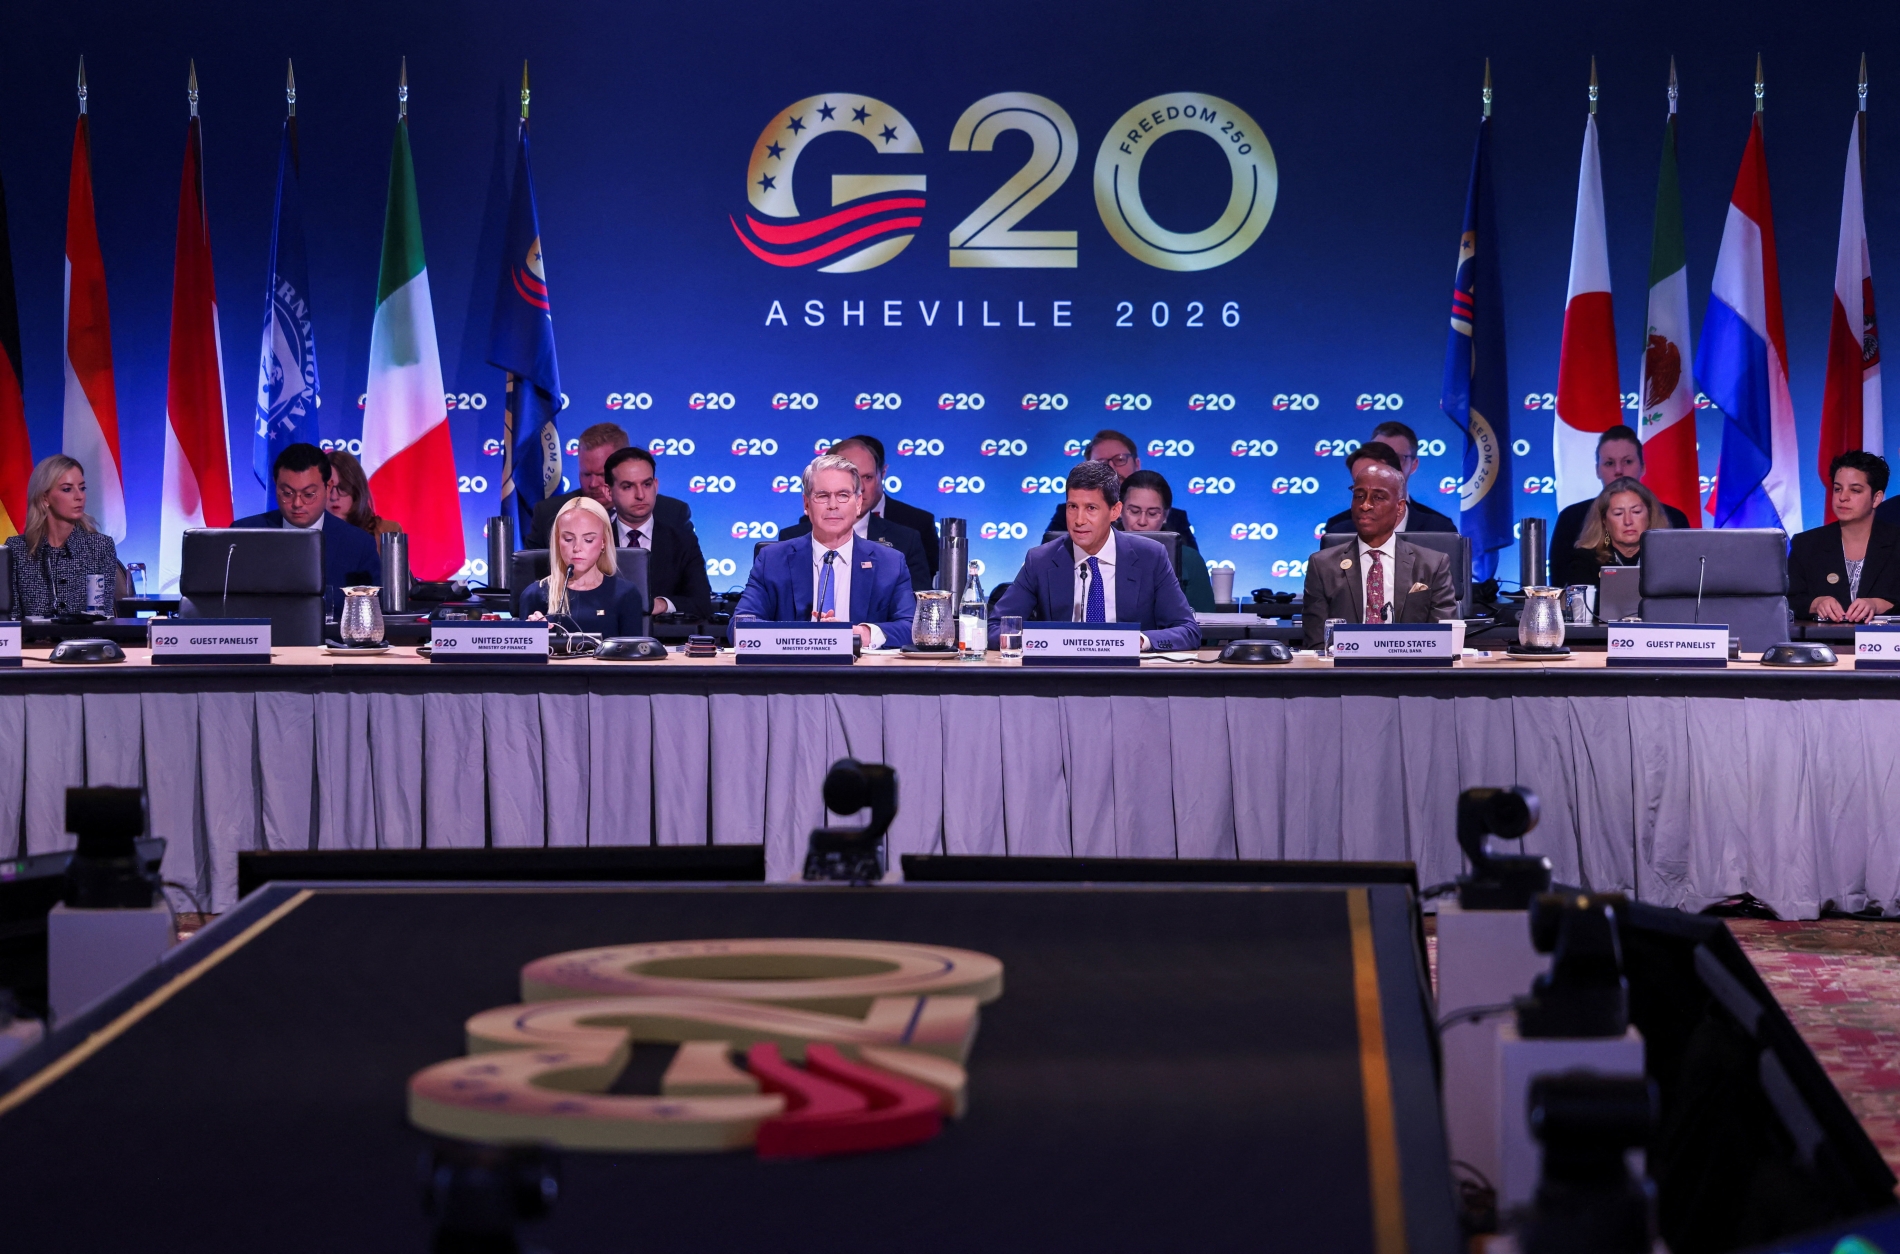
US Treasury Secretary Scott Bessent and Federal Reserve Chair Kevin Warsh attending the G20 meeting of finance ministers and central bank governors in Asheville, North Carolina, on 31 August 2026.

Agree to disagree

In 2026, that broad system of coordination is under strain. G20 finance ministers failed to agree on a joint communiqué in Asheville, North Carolina, at the end of August. The deadlock exposed sharp differences over global trade imbalances, non-market policies, energy supply chains, critical minerals, and debt, which hangs over all of them. Public and private liabilities worldwide are estimated at a staggering $353tn, much of it concentrated in the largest economies, led by the US, China, and Japan. Elsewhere, inflation remains high, such as 30.4% in Argentina and 28.6% in Türkiye.

China objected to the language on trade imbalances, non-market policies, and reliance on exports to drive growth. The Americans believe Beijing is sensitive to the pressure Chinese exports (especially low-cost goods) exert on US industry. The US has urged other G20 members to confront China’s export-led model.

In August, it accused more than 40 countries of involvement in a “hidden trans-shipment network” that reroutes Chinese goods into the US to circumvent tariffs. Earlier in the year, Beijing expanded its zero-tariff regime to imports from 63 countries, most of them developing economies in Asia, Africa and Latin America. Chinese imports rose 22% year-on-year in the first seven months. Tariff cuts alone do not account for the increase.

The dispute spilt directly into the G20 text. According to the US, China objected to paragraphs covering war and regional conflicts, including the closure of the Strait of Hormuz, global trade imbalances, export dependence as a driver of growth, and sovereign debt restructuring. Beijing says it is not to blame for global imbalances, as arguments continue over China’s large trade surpluses and the weight of exports in its economy.

The G20 is no stranger to disputes, especially since Russia’s invasion of Ukraine in 2022. The next test comes in Miami on 14-15 December. America’s trade and fiscal deficits, and mounting debt, could be a major issue in its competition with China. Iran may be another fault line. The US wants other G20 members to tighten sanctions on Iran and hold it responsible for disruptions to energy supplies and rising prices, but this is likely to get some pushback.
EPA
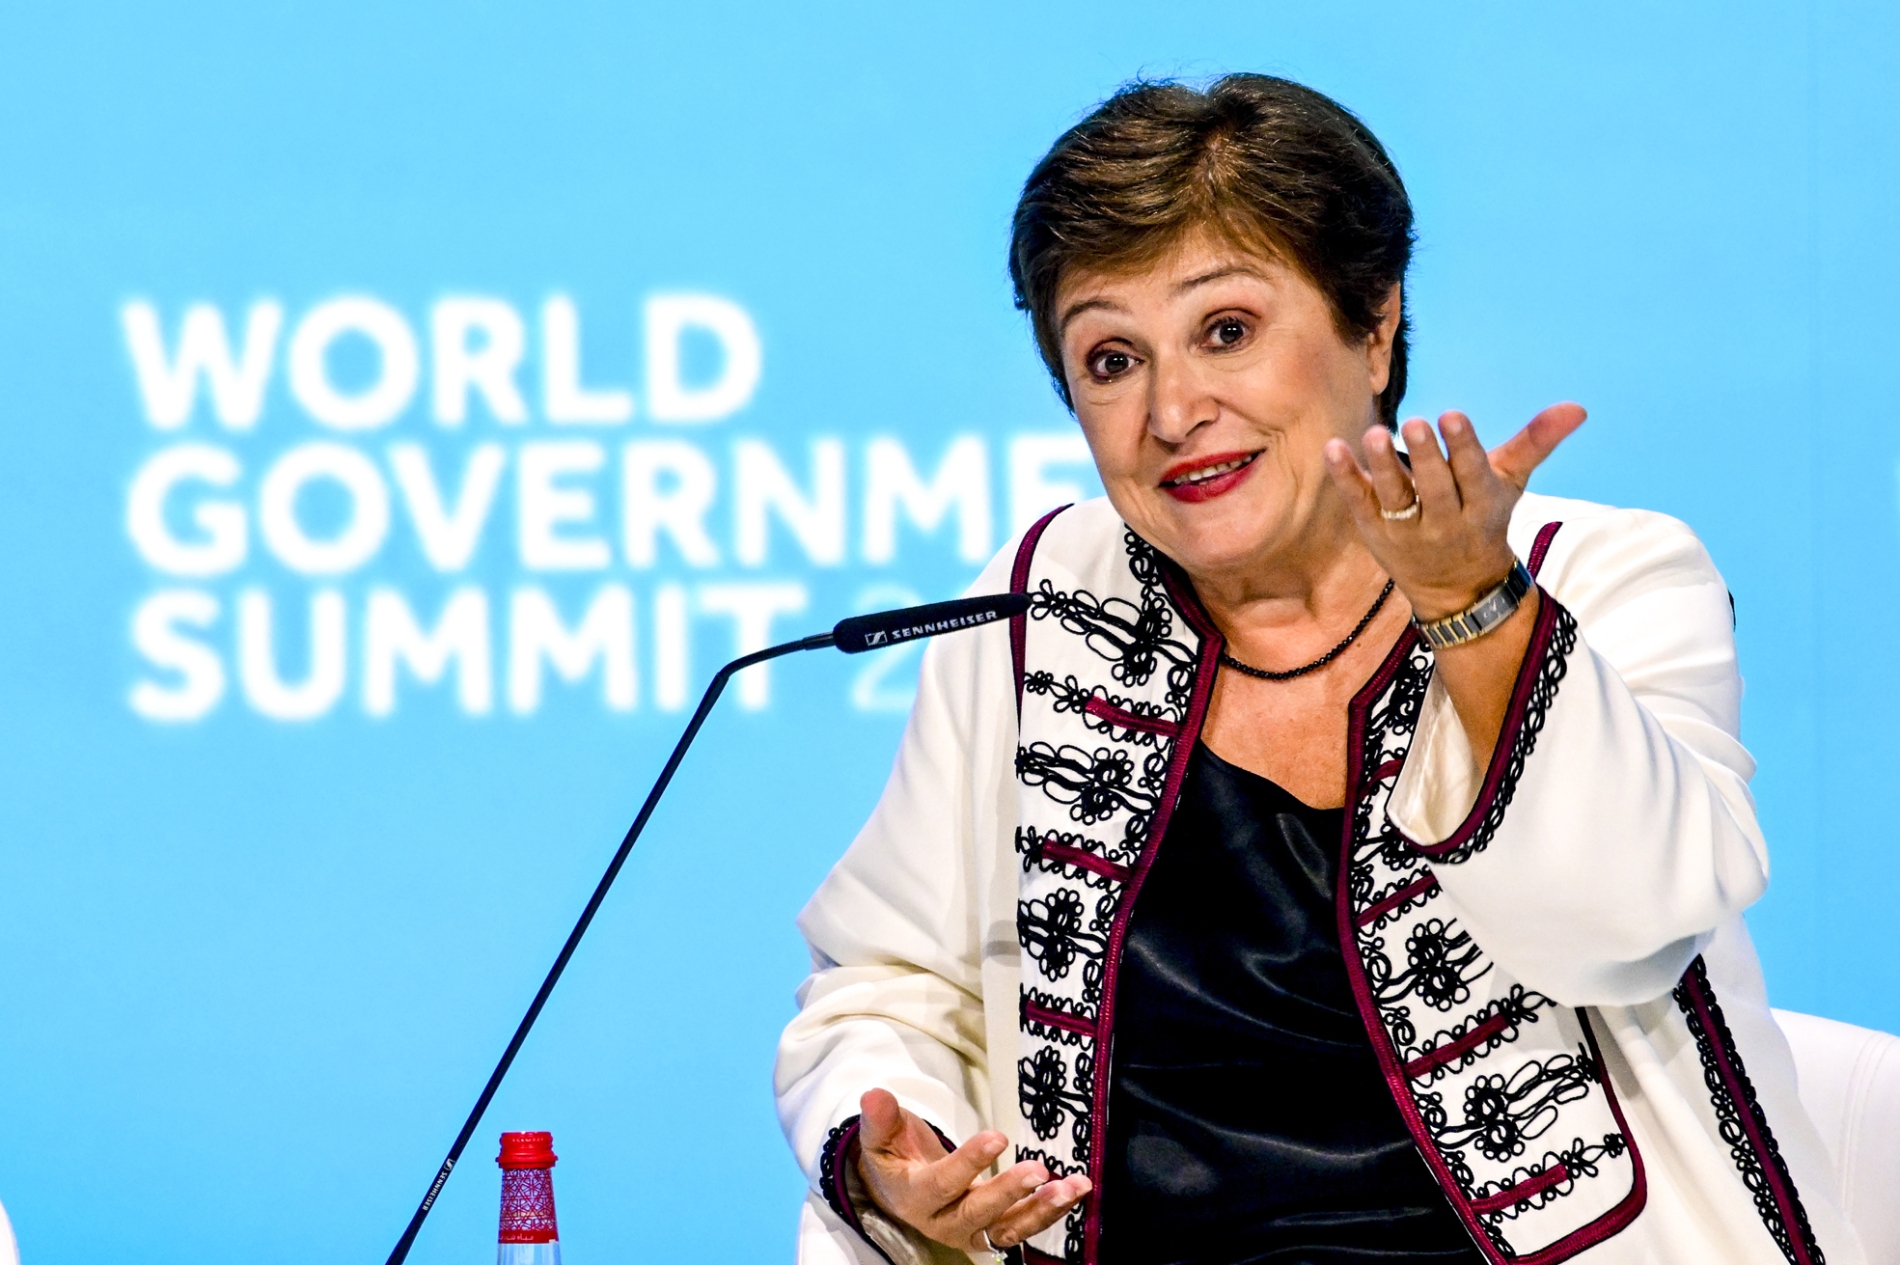
Director General of the International Monetary Fund, Kristalina Georgieva, while attending the World Government Summit session in Dubai on 12 February 2024.

IMF warning

The International Monetary Fund has entered the US-China argument on growth, debt, and exports. At Asheville, IMF head Kristalina Georgieva warned that global public debt was now approaching 100% of world GDP, had already surpassed its highest level since World War II, and was still rising. She likened the path of debt to an ascending staircase: sharp jumps during shocks, followed by only modest declines, if any. Her prescription was “sound fiscal and monetary policies”.

Central banks should keep their focus on price stability, she said, while fiscal authorities need credible medium-term plans to bring public finances under control. For the Bretton Woods institutions, led by the IMF, such discipline is essential if the world is to prevent debt from becoming an even bigger problem and reduce the risk of economic contraction.
Global public debt is now approaching 100% of world GDP, having already surpassed its highest level since World War II, and is still rising

Agreement ends there, however. Governments argue over what is holding back growth, how interest rates should respond, and how to manage mounting debt. Faster growth appears the most attractive escape from the debt trap, but what kind of economic model will deliver that growth, and why is the existing model faltering?

This year's G20 agenda pushed familiar themes such as climate change, inequality, and development further into the background, as the US emphasised removing non-tariff trade barriers, stronger private-sector investment, and action on economic imbalances and sovereign debt. The IMF sets out a different hierarchy of priorities: price stability, sound fiscal and monetary policy, structural reform, and credible medium-term fiscal plans that can support stronger, more balanced growth.

The Oxford Institute expects global growth to fall to 2.5% by the end of this year, citing adverse international conditions and political uncertainty. Before the outbreak of the Iran war in February, growth of 3.1% had been expected. 

The US Treasury has long argued that "non-market economies that rely on cheap exports do not offer a sustainable solution," but dozens of economies now depend heavily on industrial exports. It is a central pillar of global production and supply chains, and one of the defining features of globalisation. The G20 may broadly agree that growth belongs at the centre of the agenda, but does not agree on the model that should produce it.

LUDOVIC MARIN / AFP
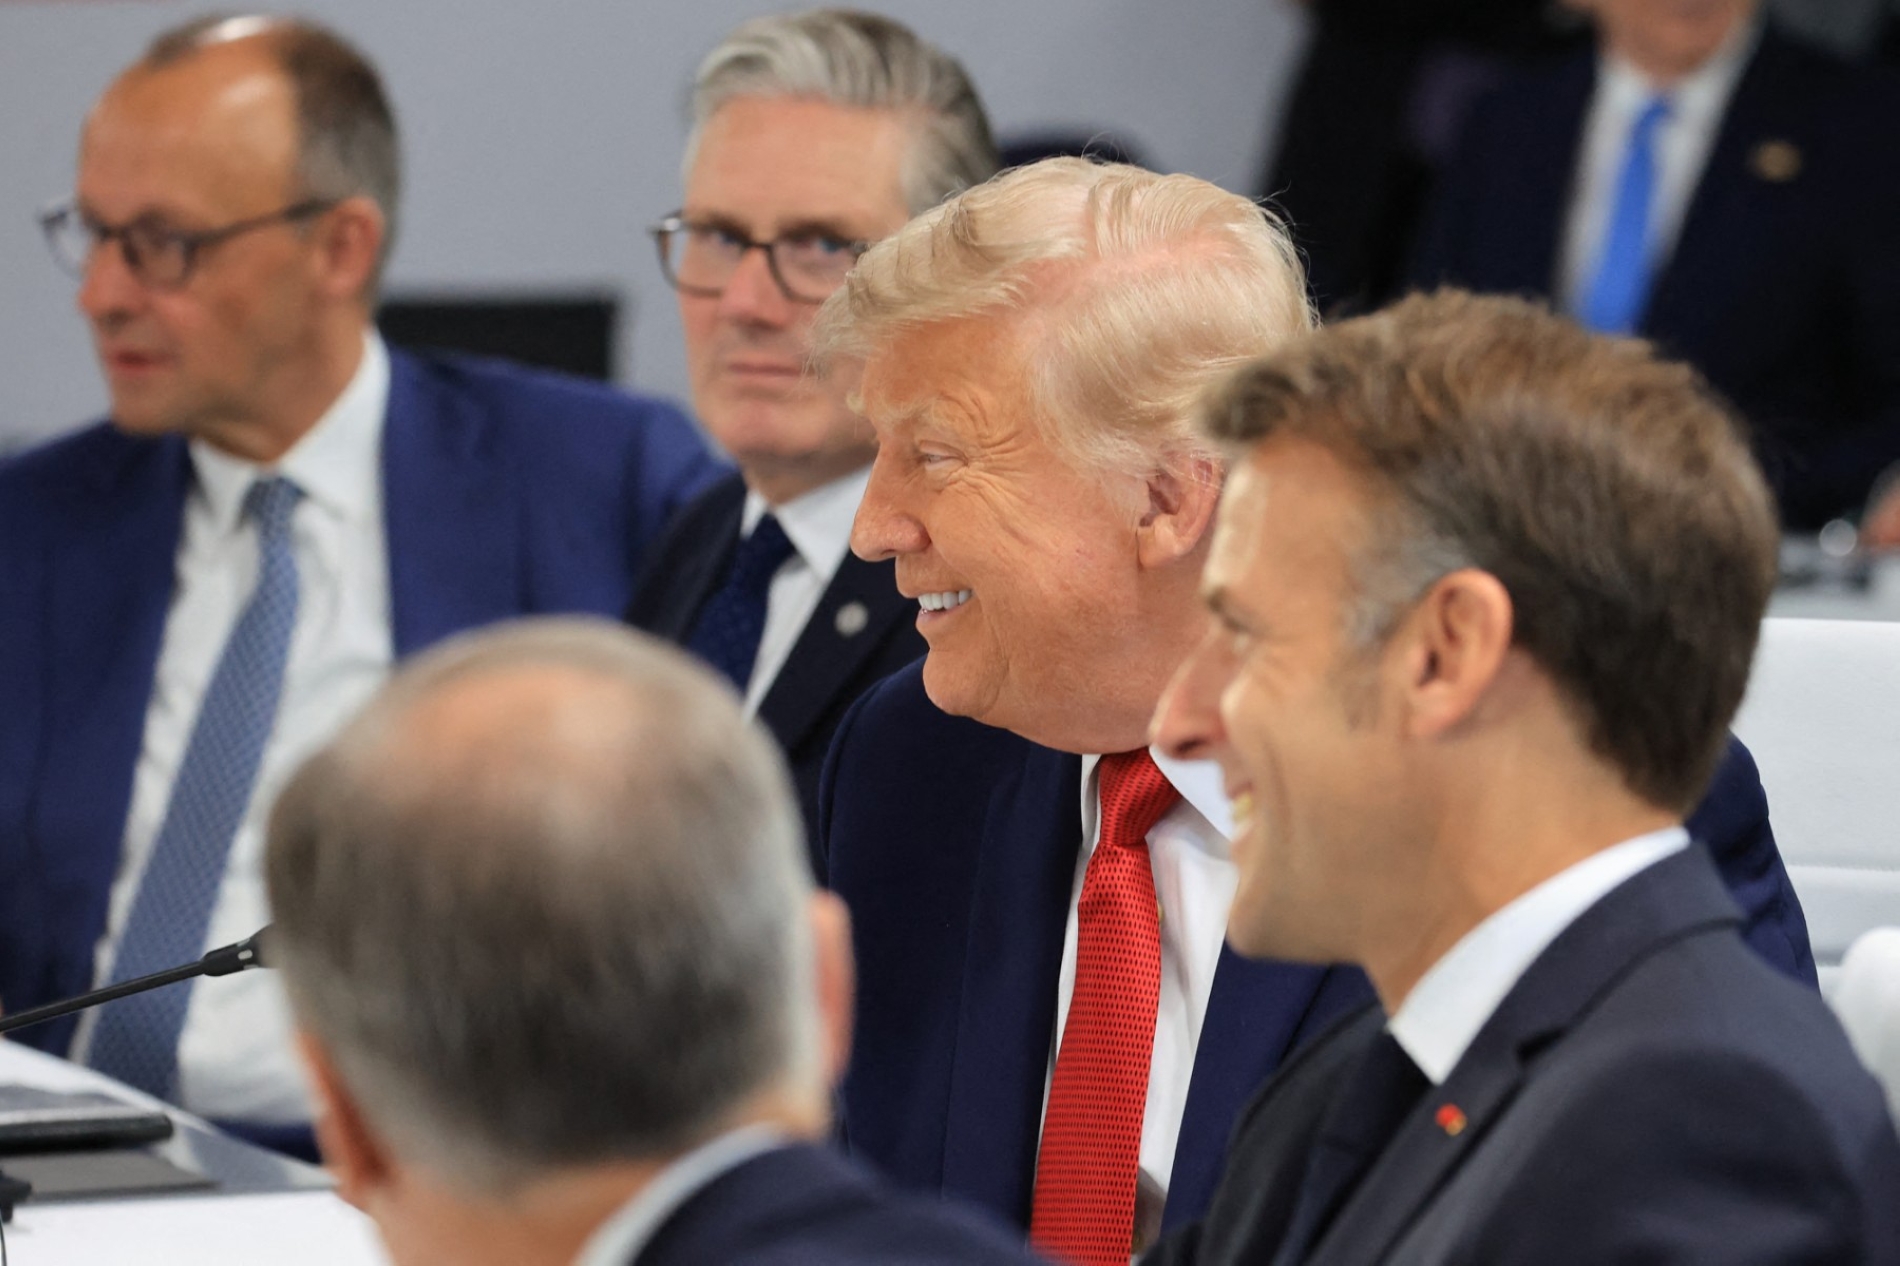
Germany's Chancellor Friedrich Merz, Britain's Prime Minister Keir Starmer, US President Donald Trump and France's President Emmanuel Macron attend a working meeting with the OECD at the G7 summit in Evian, France, on 17 June 2026.

Bond markets react

The OECD group of rich-world countries sees another danger gathering in the bond markets. High debt and rising borrowing costs are squeezing governments' and companies' ability to finance investment and growth, as they prepare to borrow $29tn from international bond markets in 2026, $4tn more than in 2024. OECD member states borrowed $17tn in 2025, up 7% from the previous year. Corporate borrowing also climbed to $6.8tn through bond issuance last year.

Just as long-term finance grows more expensive, governments and businesses are becoming more dependent on debt markets. Short-term interest rates across OECD economies remained relatively stable in 2025, but yields on 30-year bonds rose sharply in most countries, pushing up financing costs and refinancing risks. Abdellatif Jouahri, governor of Morocco's central bank, said decisions over raising or lowering rates are among the hardest any central bank can make, because they rarely satisfy everyone.

Borrowers and sovereign wealth funds have adjusted to higher long-term rates, though the consequences for investment and financing are still to emerge. The IMF warns that once debt hits 90% of GDP, it can slip into a vicious circle. Since Iran effectively closed the Strait of Hormuz in March, high bond yields have become a growing source of anxiety across financial markets. Inflation, interest rates, sovereign debt, and growth feed into one another.

By the end of last month, the yield on 10-year US Treasuries was 4.75%, while the two-year yield was 4.34%, according to Treasury data. The strain has led it to repurchase some of its own securities to improve market liquidity. Government and corporate borrowing from debt markets reached a record $27tn in 2025.

Artificial intelligence (AI) is adding to demand. The sums required to build AI data centres and provide the supporting energy and infrastructure are immense, making AI companies increasingly visible in debt markets. Until recently, tech firms had little need for external finance, but planned cumulative capital expenditure from 2026-30 is now at $4tn. Last year, nine of the biggest companies (known as hyper-scalers) raised a combined $122bn in bond markets, half of the sector's bond issuance worldwide.

AFP
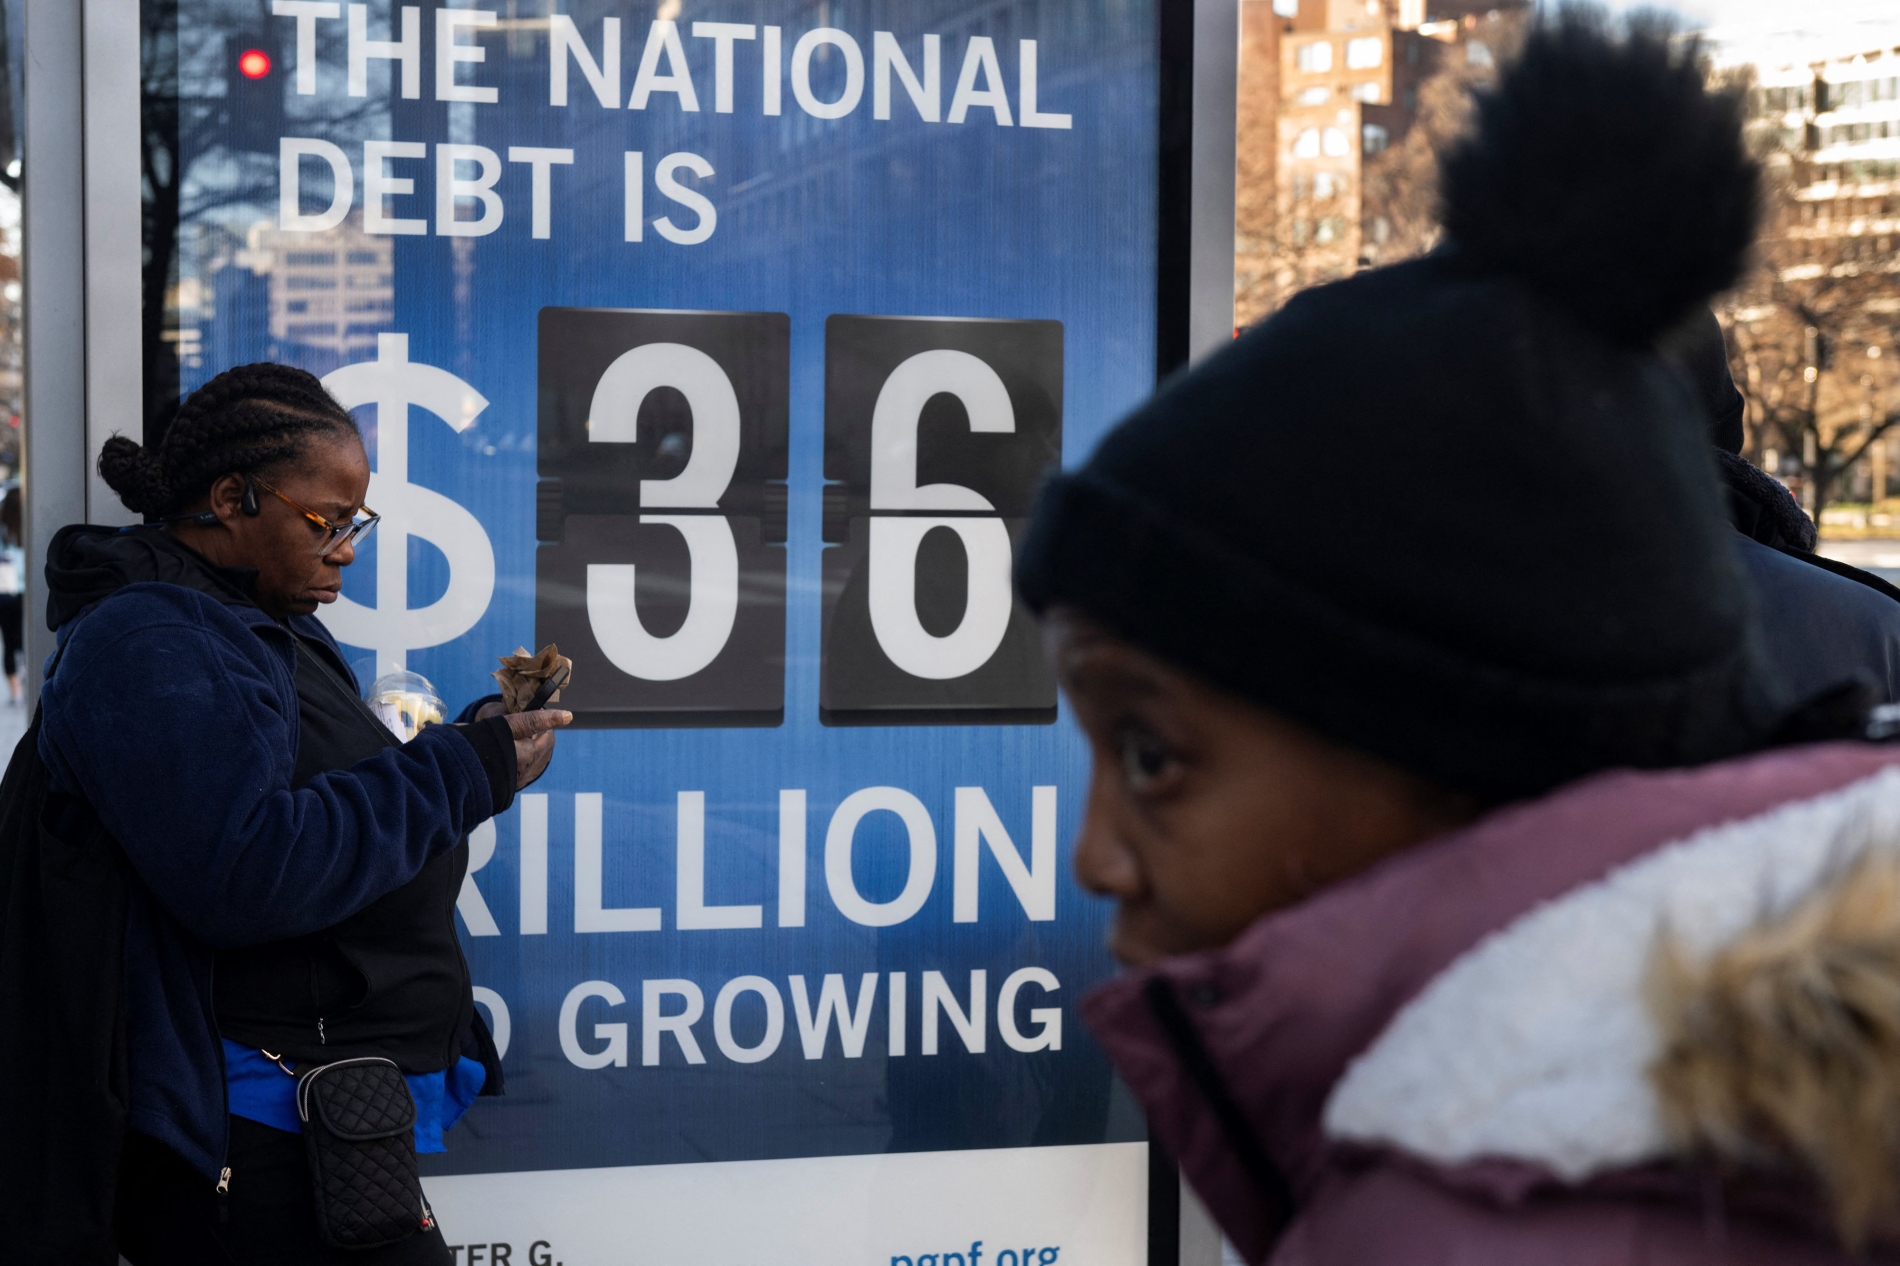
A billboard in the middle of a public street shows the size of the US debt, on 30 December, Washington, DC, in 2024.

Threat to growth

The rise in US debt is now a global concern, as it passed $40tn in August. The repercussions reach far beyond America. The dollar sits at the centre of foreign-exchange markets and cross-border payments, while US Treasuries are core low-risk assets in global finance, widely used as collateral and benchmarks for pricing other instruments. Any sustained rise in US borrowing costs, or disruption in the Treasury market, can therefore travel quickly through the financial system, raising funding costs and amplifying volatility elsewhere.

Dan Coatsworth, a financial analyst at investor AJ Bell, said an ordinary American worker would need more than 615 million years to earn the equivalent of the debt's principal value, which has doubled over the past decade. US debt has risen from $5tn in 2000 to $18tn in 2015 and $27tn in 2020. Servicing it is now a fiscal burden of historic scale. Annual debt-servicing costs are $1tn, more than defence spending, while net interest costs alone reached about $104bn in July.

Medium-term risks also depend on who owns the debt. The French public-policy institute Fondation IFRAP notes that foreign investors hold 53% of sovereign debt in France, 42% in Spain, 32% in the UK, 27% in Italy, and 23% in the US. That dependence can leave governments exposed to shifts in global financial sentiment.

If foreign investors pull back from sovereign bonds, governments may have to offer higher yields to attract funding. Debt-servicing costs then rise, squeezing public finances. Economies that rely most heavily on external investors are the most vulnerable, so debt is not just a question of scale; ownership matters, as does dependence on foreign capital.

US debt has risen from $5tn in 2000 to $18tn in 2015 and $27tn in 2020. Servicing it is now a fiscal burden of historic scale

Identifying the ultimate owners of sovereign bonds can be difficult. Holdings may pass through layers of intermediaries and financial centres, making the final beneficial owner difficult to trace. The Cayman Islands, the Bahamas, and Singapore feature prominently in data on foreign debt holdings, although their presence does not necessarily mean investors are trying to conceal their identities.

The Arab world

Because its economies do not form a single bloc, the Arab world occupies a different place in the global debt crisis. Gulf states have substantial fiscal buffers, reserves, and sovereign wealth funds to protect against higher borrowing costs and market volatility, but other Arab economies face heavier debt burdens, tighter public finances, and rising debt-servicing costs.

The crisis therefore exposes a clear regional divide. Some states have financial surpluses and sovereign assets to deploy in global markets; others remain far more dependent on external borrowing, aid and international finance. As bond yields rise worldwide, that divide becomes harder to ignore. Higher financing costs squeeze debtors and make investment, and therefore future growth, more expensive to fund.

font change