
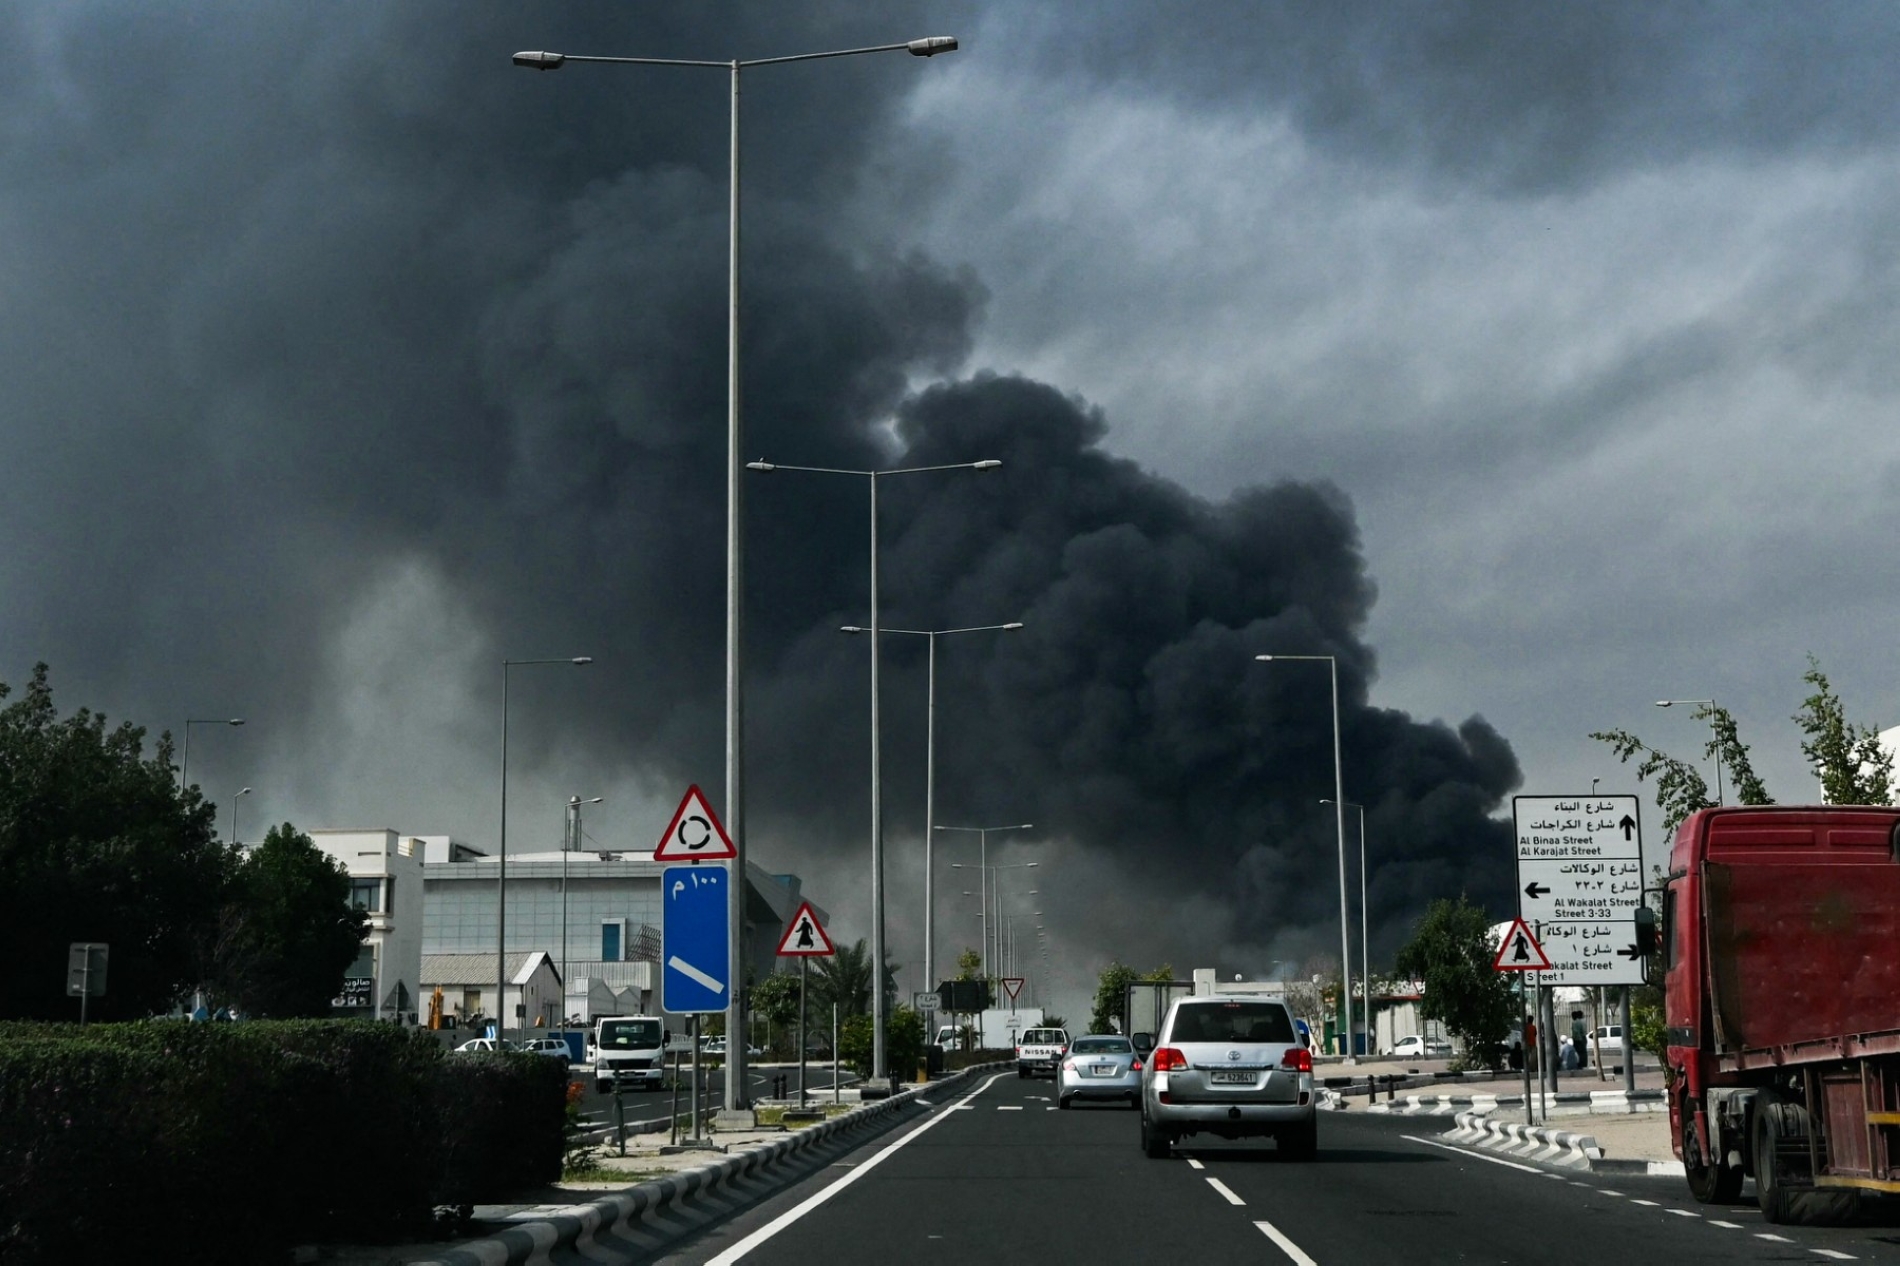
When QatarEnergy secured a $3bn loan from four major Chinese banks in October 2026, it appeared at first glance to be a routine financing agreement between a national energy company and international lenders. Its timing, however, made it far more significant than a figure on a balance sheet. The loan came as Qatar was trying to restore liquefied natural gas exports following the strikes that damaged its facilities at Ras Laffan, while shipping through the Strait of Hormuz remained sporadic and exposed to the risks of war.
Three contests converged in this single transaction: Qatar’s effort to reclaim its standing as a reliable gas supplier, China’s drive to secure long-term energy supplies and a broader struggle for influence in a market where finance can no longer be separated from security and maritime transport.
The loan does not mean that China has bought Qatar’s political loyalty or become the security guarantor of its gas facilities, but it does reveal the growing interdependence between the two countries. Qatar needs liquidity, customers, ships and commercial flexibility; China needs competitively priced gas that it cannot fully replace from other sources. China is helping Qatar weather the crisis and restore its presence, but in the process it is building long-term influence within the country’s gas industry.
The five-year facility was provided by Bank of China, the Industrial and Commercial Bank of China, the Agricultural Bank of China and China Construction Bank (Asia). According to published information, it was priced at 50 basis points above the Secured Overnight Financing Rate, or SOFR—a competitive rate given the heightened risks across the region.
The proceeds will be used for general working-capital purposes. This is an important distinction: the transaction was not announced as dedicated financing for repairs at Ras Laffan or for the construction of a particular production train. Its timing can reasonably be linked to the need to offset weaker cash flow and finance operations, repairs and insurance. It would be inaccurate, however, to portray it as a Chinese loan specifically intended to rebuild facilities destroyed in Iranian strikes.
Nor is there any publicly available evidence that Qatar pledged gas reserves as collateral or granted the Chinese banks rights over project management or gas pricing. The facility is denominated in US dollars and linked to an American interest-rate benchmark, rather than the renminbi. It therefore does not represent a departure from the dollar-based financial system.
The loan also remains modest when set against the approximately $28.75bn invested in the North Field East expansion, or Qatar’s plan to increase its LNG production capacity from 77 million tonnes a year to 142 million tonnes by the end of the decade. It gives QatarEnergy time and liquidity but does not transfer control of the country’s gas industry to its lenders.
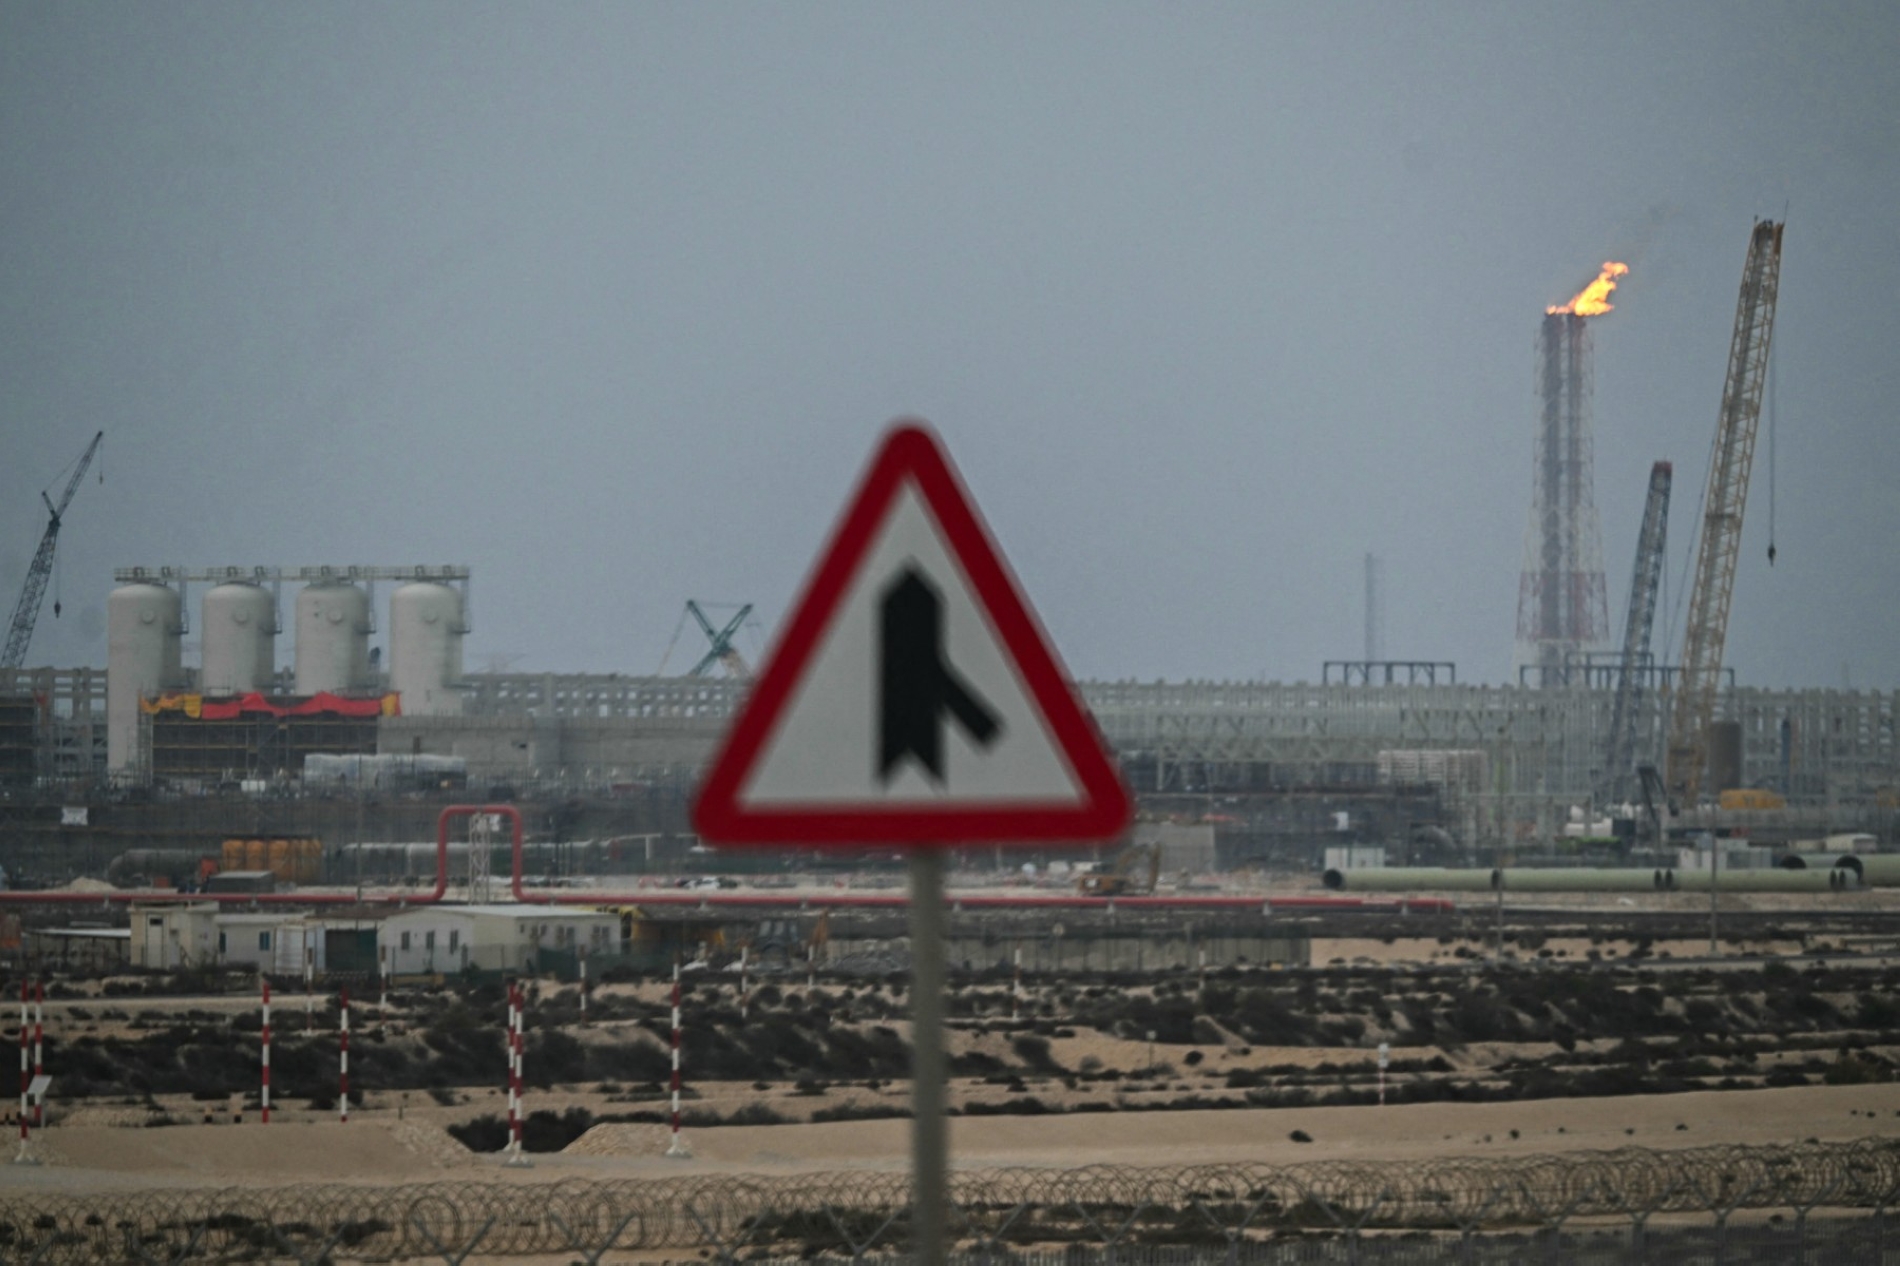
The strikes on Ras Laffan knocked approximately 12.8 million tonnes a year of LNG capacity out of service, equivalent to around 17% of Qatar’s export capacity. Saad Sherida Al-Kaabi, Qatar’s Minister of State for Energy Affairs and the President and CEO of QatarEnergy, said the lost capacity represented about $20bn in annual revenue. Production of condensates, liquefied petroleum gas, helium and naphtha was also affected.
Initial estimates suggested that repairing the two damaged liquefaction trains could take between three and five years. The Pearl gas-to-liquids plant, known as Pearl GTL, has begun restoring part of its operations, although repairs to the damaged section are expected to continue into early 2027.
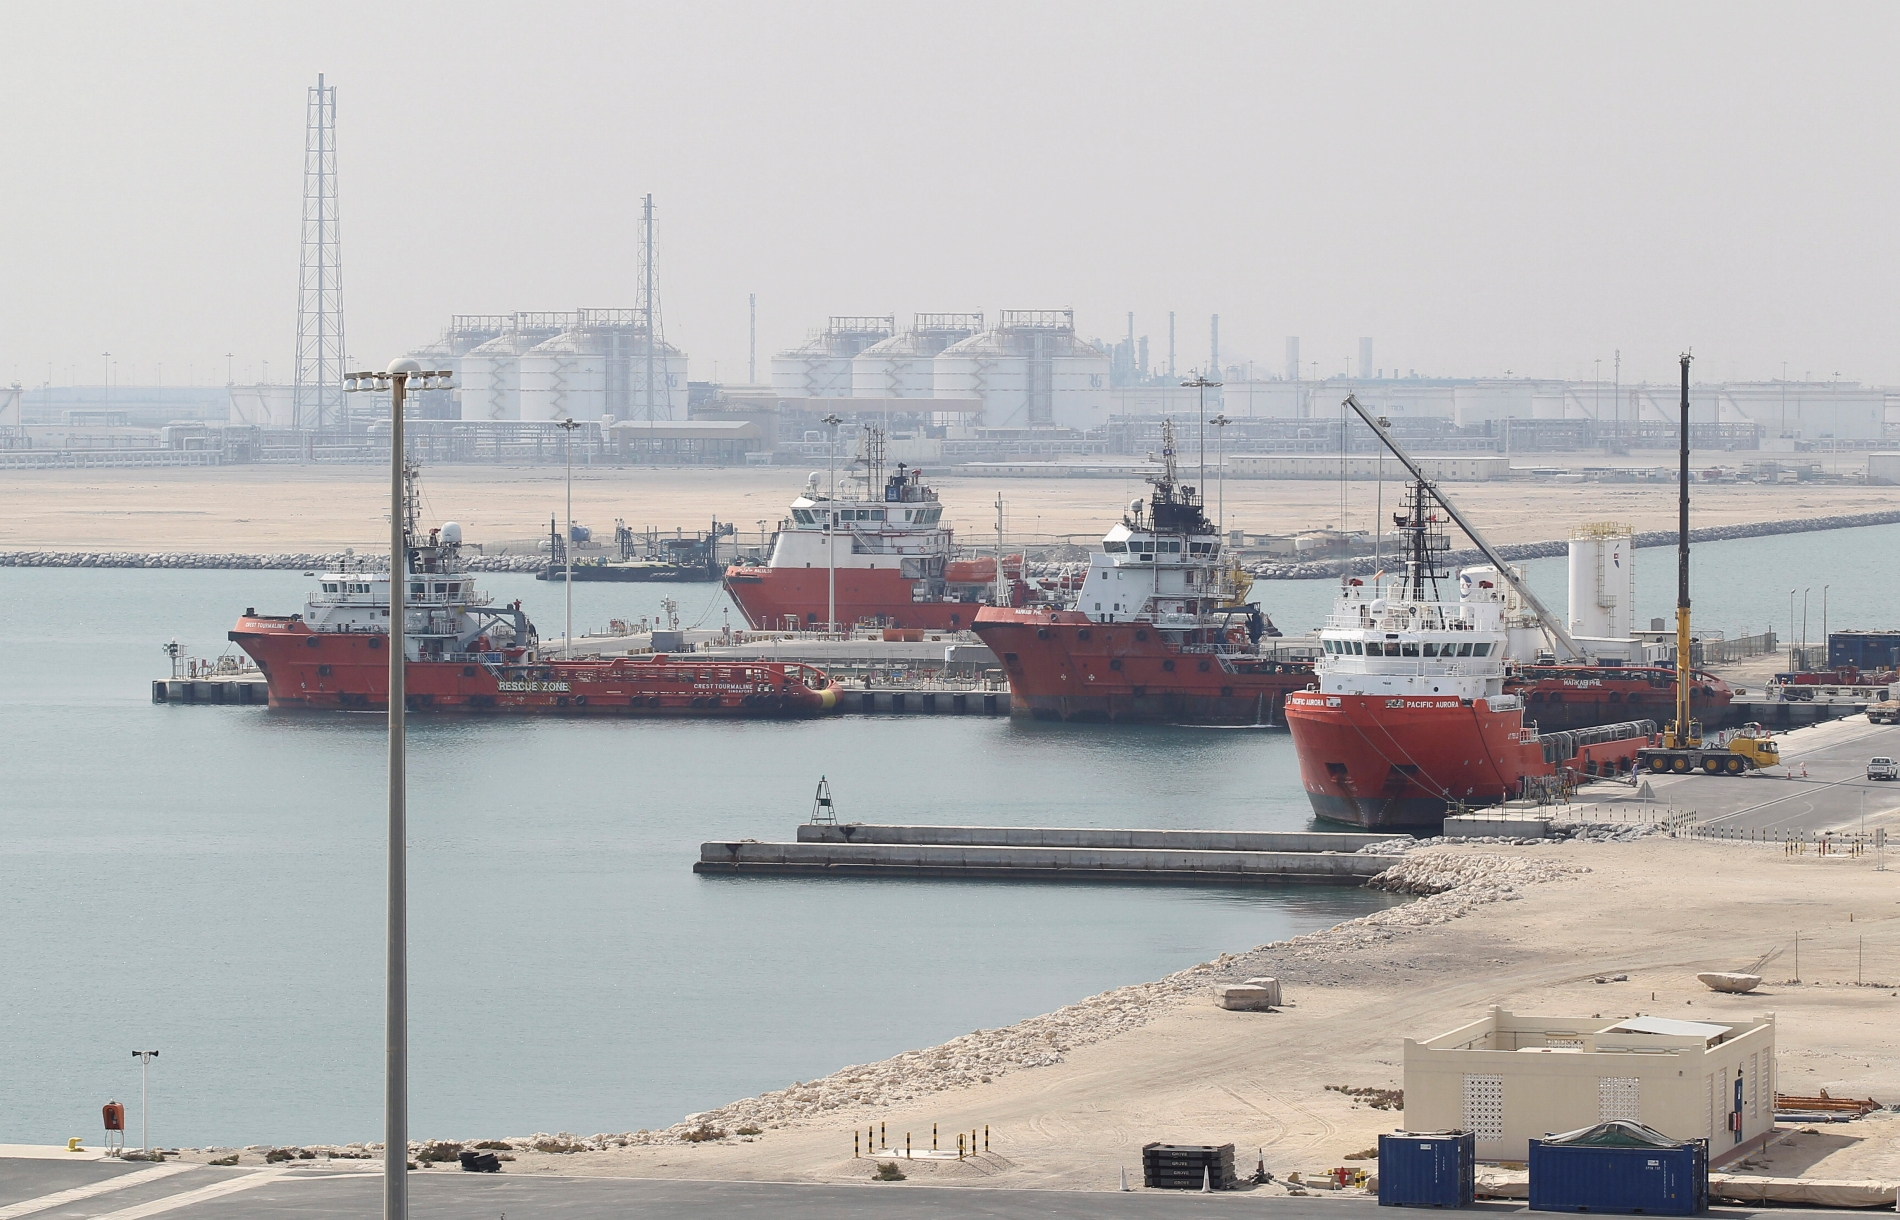
Recovering production, however, would not resolve the entire problem. LNG exported from Ras Laffan must pass through the Strait of Hormuz, and Qatar has no pipeline to an alternative port capable of handling comparable volumes. The liquefaction trains may be operational and the storage tanks full, but gas cannot be converted into revenue if carriers cannot enter and leave safely. The fundamental vulnerability of Qatari gas lies neither in a shortage of buyers nor in inadequate reserves, but in the fact that production sits behind a single maritime chokepoint for which Doha has no complete alternative.
During the first six months of the war, Qatar’s LNG exports fell by around 96%. By late August, the country had lost close to $24bn in sales, according to calculations based on shipping and price data. Traffic recovered partially in September, when between 19 and 21 LNG cargoes passed through the Strait of Hormuz. Thirteen of them were Qatari shipments, according to one vessel-tracking company.
Some carriers made the passage with their automatic identification system transponders switched off, while other companies continued to avoid the area or demanded steep insurance premiums. By mid-October, Kpler estimated that Qatar’s exports for the month were on course to reach no more than about 600,000 tonnes, compared with approximately 1.6 million tonnes in September, as attacks resumed. QatarEnergy also extended its force majeure declarations for some Asian customers into November and for European customers into December.
To keep at least part of the trade flowing, Qatar and other Gulf producers have resorted to arrangements that are unusual in the LNG business, including ship-to-ship transfers outside the highest-risk area. One carrier crosses the strait with the LNG before transferring its cargo to another vessel, which then completes the longer voyage to the buyer.