AI data centres: the costliest infrastructure race in history?https://en.majalla.com/node/333076/business-economy/ai-data-centres-costliest-infrastructure-race-history
From the outside, a data centre looks much like a vast industrial building: a warehouse surrounded by fences and security systems. What happens inside it, however, places it in an entirely different economic category. The walls may last for decades, but the servers, processors and networking equipment have only a few years before they lose their competitive edge and need to be replaced.
AI infrastructure is therefore not built just once. The cycle begins with purchasing land, installing cooling systems, and providing power connections. Every four to six years, however, it absorbs another wave of capital in the form of more powerful, densely packed processors and servers. In this sense, a data centre represents a recurring commitment to buying new chips, housed inside a building constructed only once.
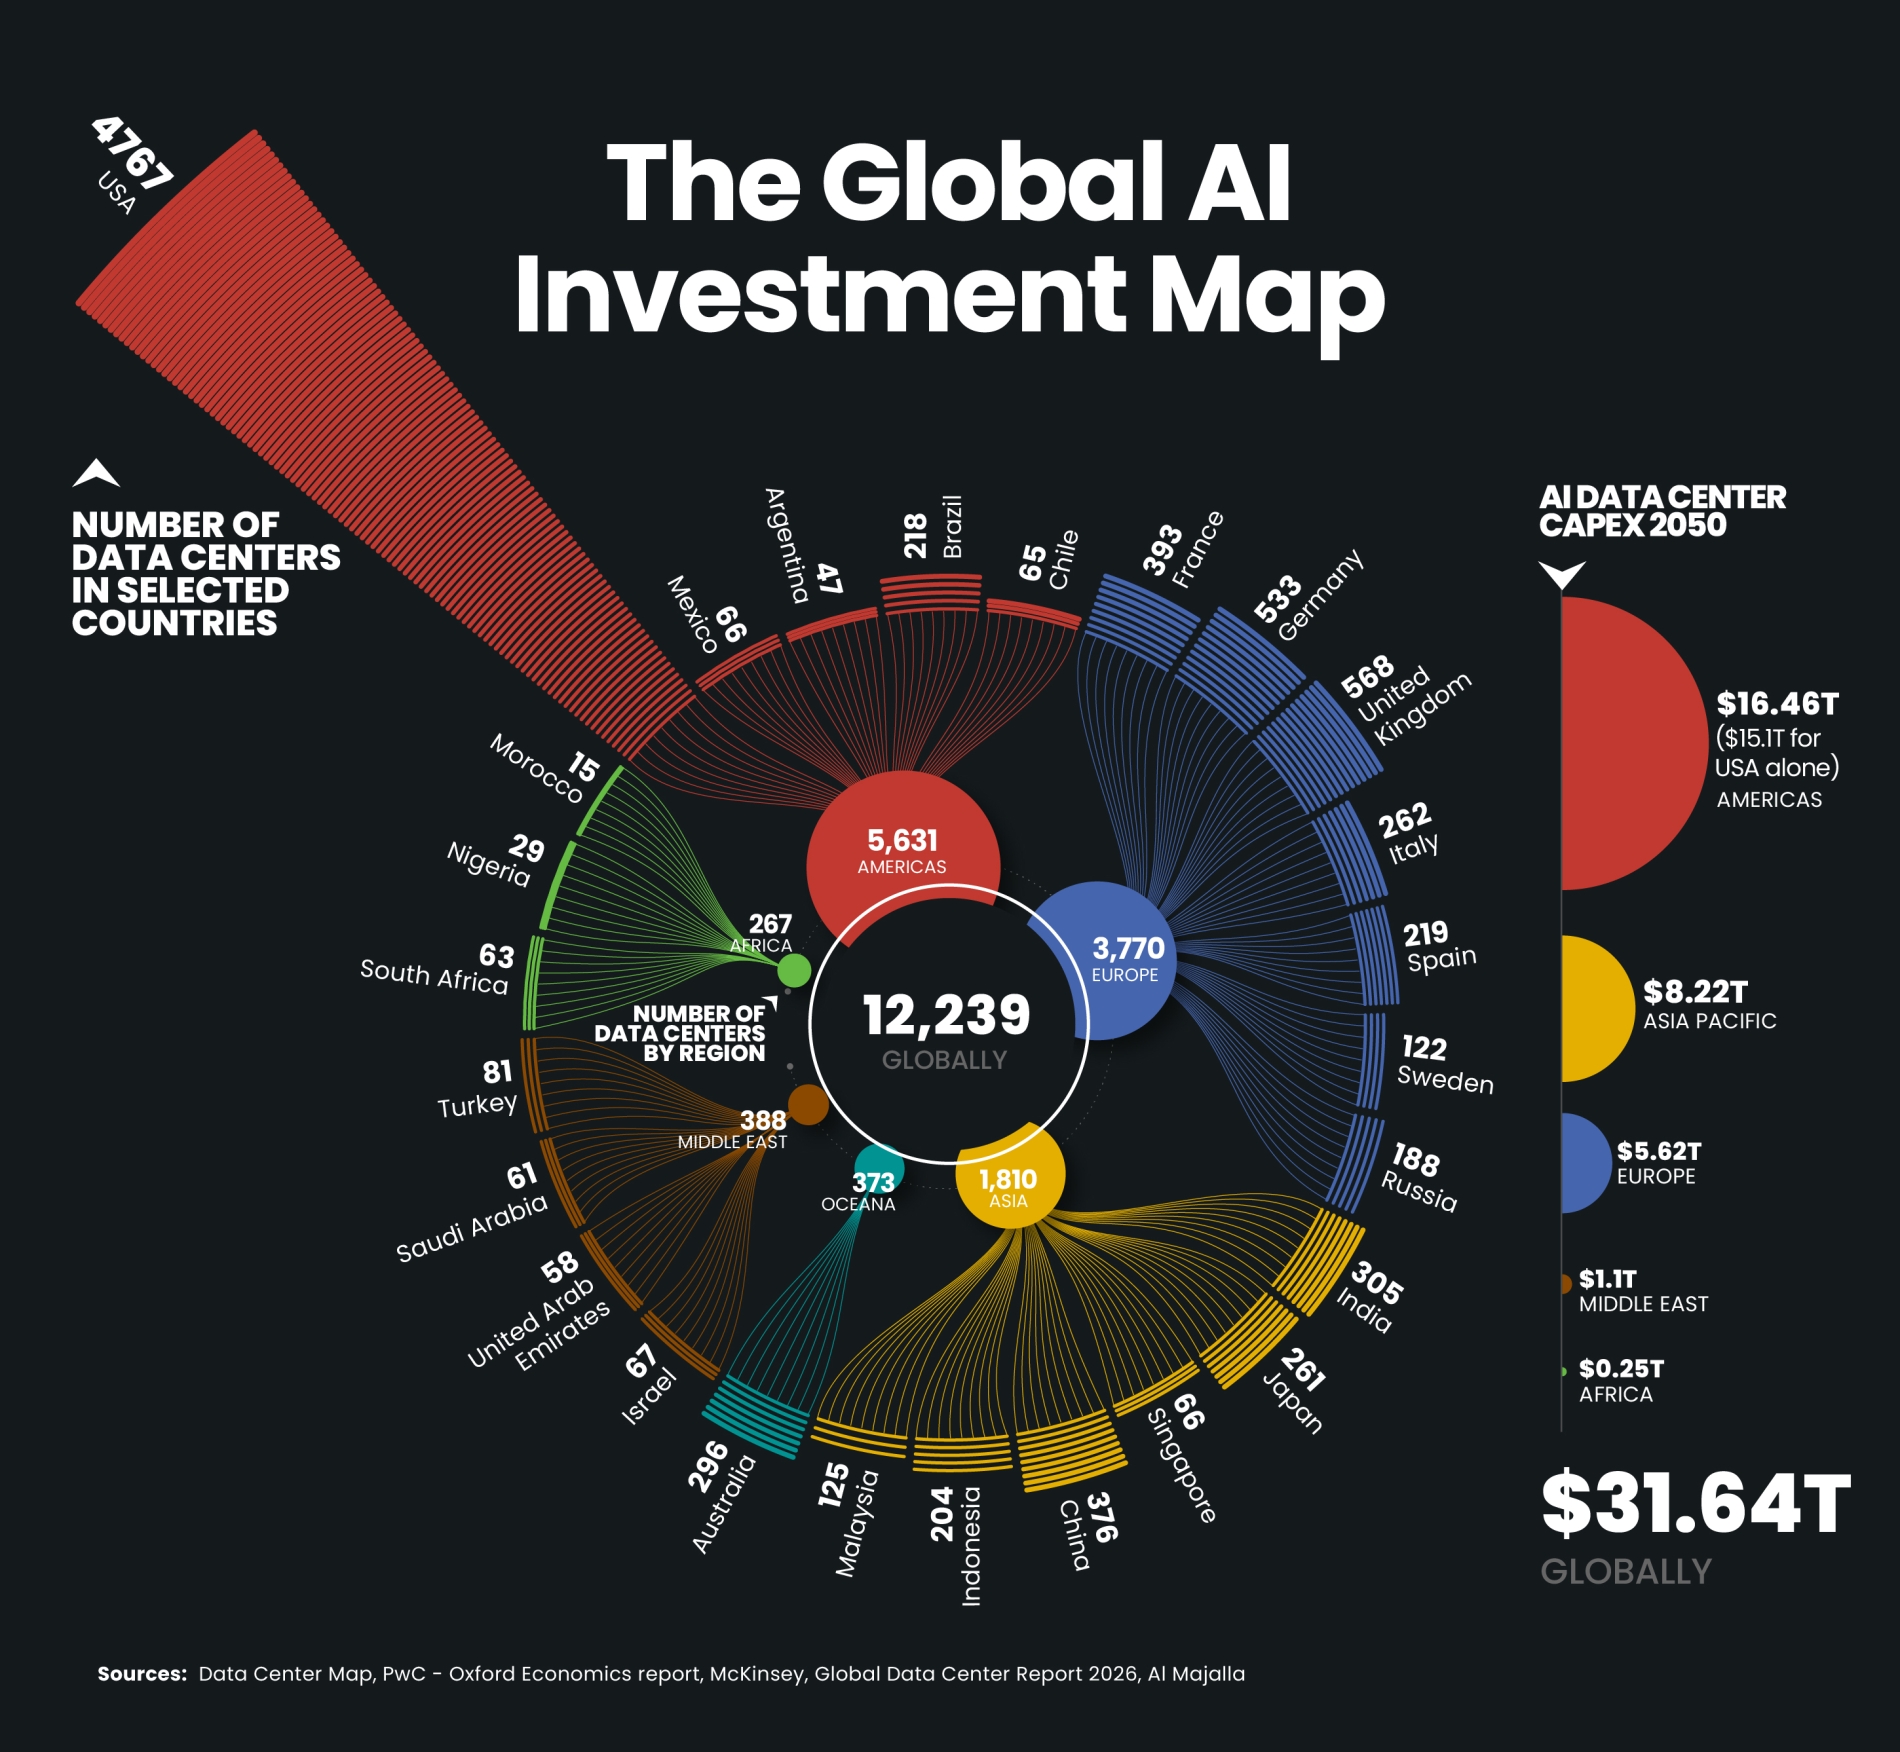
This cycle underpins the enormous estimate published by PwC, based on modelling by Oxford Economics. Under its central scenario, the data-centre sector could attract $31.6tn in cumulative capital expenditure between 2026 and 2050, measured in 2025 prices. If AI adoption accelerates, spending could approach $50tn. It could fall to about $22tn if adoption and economic growth prove slower than expected.
This does not mean that the world will spend $31.6tn in 2050 alone, nor does the figure apply exclusively to facilities dedicated to AI. It is an estimate of total spending on the data centres required to meet growing digital demand, with AI at its core. Under the central scenario, annual investment rises from about $800bn in 2026 to $1.1tn in 2030 and $1.8tn in 2050.
The striking feature is not simply the scale of investment, but where the money will go. The relative share devoted to buildings, infrastructure, power and cooling systems declines over time, while information and communications technology equipment rises from 70% of total expenditure in 2026 to 93% in 2050.
The study estimates that every dollar spent on constructing the building and its basic infrastructure leads, over the project’s lifetime, to about $12 of expenditure on servers, graphics processing units, storage and networking equipment. A data centre operating for 20 years may require between three and five complete rounds of equipment replacement.
This is where such investment differs from previous cycles involving railways, electricity grids and even the internet. In those cases, expenditure was concentrated on laying tracks, installing power lines or deploying telecommunications cables, before gradually declining as the networks were completed. With data centres, the cost does not end when construction is finished, because the computational heart of the facility ages rapidly.
That defining feature also carries an inherent risk. For the equipment-replacement cycle to continue every few years, the revenue generated by AI must grow at a comparable rate. If applications spread more slowly, service prices fall, or productivity gains disappoint, vast facilities could become surplus capacity with too few customers.
The risk is greater for specialist computing providers and smaller model developers than for the largest cloud-computing companies, because they have less capacity to sign long-term contracts or withstand volatility in markets and financing conditions.
The data-centre sector could attract $31.6tn-$50tn in cumulative capital expenditure between 2026 and 2050, measured in 2025 prices
PwC estimates
Towering role
The money will not be distributed automatically according to the size of each economy or population. Generating demand is not enough; what matters is whether a country can host it. The study expects the Americas to receive $16.5tn by 2050, of which the United States alone accounts for $15.1tn, or about 48% of the global total. The remaining sum of approximately $1.4tn is divided between Canada and Latin America.
America's lead is not merely a product of the size of its economy. The country brings together the largest cloud-computing companies, developers of advanced AI models, capital, talent and start-ups, as well as US firms' pivotal role in semiconductor design. This concentration reinforces itself: existing infrastructure attracts more companies, financing and suppliers, strengthening the market's advantage rather than eroding it.
Asia-Pacific comes next, with about $8.2tn, driven by the scale of demand in China and India and the expansion of the digital economy. Even so, its share remains below its weight in the global economy. It is also the region most sensitive to the pace of AI adoption and restrictions on semiconductor trade.
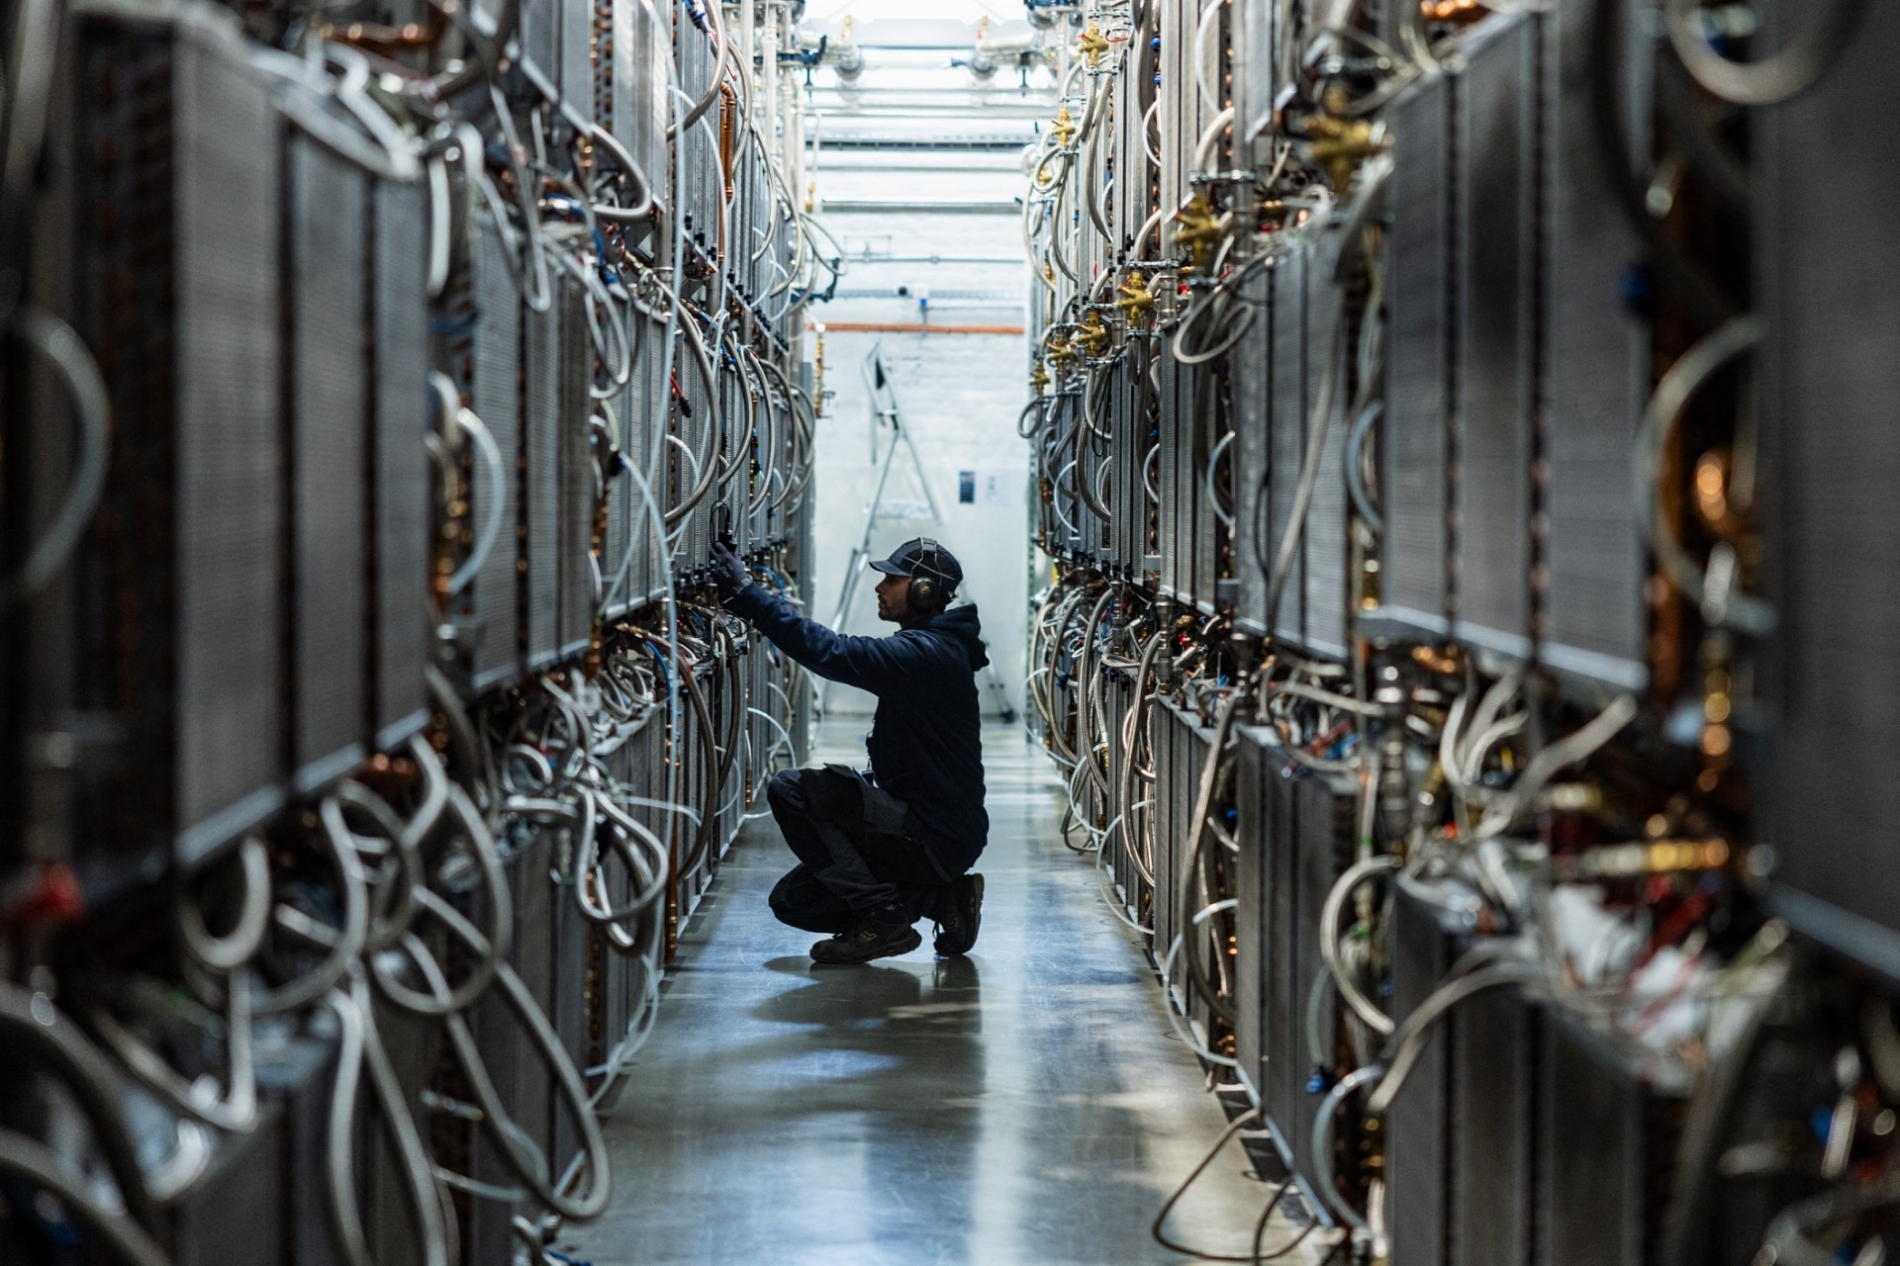
An operator works at the data centre of French company OVHcloud in Roubaix, northern France, on 3 April 2025.
Europe is expected to attract about $5.6tn, another share that falls short of its economic weight. The continent does not lack demand or industrial expertise, but it faces constrained electricity grids, slow planning and permitting procedures, and regulatory differences among countries. The Nordic countries, by contrast, benefit from renewable electricity and cooler climates that reduce cooling costs.
The Middle East is expected to receive $1.1tn. Although modest compared with the figures for the United States and Asia, the region is projected to record the fastest relative growth from a limited base, benefiting from its ability to combine financing, energy, land and swift government decision-making.
Africa is expected to receive about $255bn. Much of this investment will go towards essential digital infrastructure that the continent needs regardless of how quickly AI spreads. South Africa remains its most established market, while Kenya, Nigeria and Ghana are emerging as promising destinations.
Restrictions on semiconductors reduce or delay investment, whereas data sovereignty redistributes it, albeit at the expense of the economies of scale
Securing power
Raising money does not appear to be the biggest obstacle in this investment cycle. Technology giants, sovereign wealth funds and infrastructure investors can provide considerable financing. The harder challenge is securing enough electricity, delivering it to the site when needed, and maintaining a reliable round-the-clock supply.
Data centres consumed about 415 terawatt-hours of electricity worldwide in 2024, equivalent to 1.5% of global consumption. The International Energy Agency expects this figure to more than double to approximately 945 terawatt-hours by 2030, slightly more than Japan consumes today.
A share approaching 3% of global electricity use may not seem extraordinary, but data centres are not evenly dispersed. They cluster around locations that offer fibre-optic connections, customers and established cloud-computing networks. Their impact on an individual city, state or electricity grid can therefore be far greater than the global average suggests.
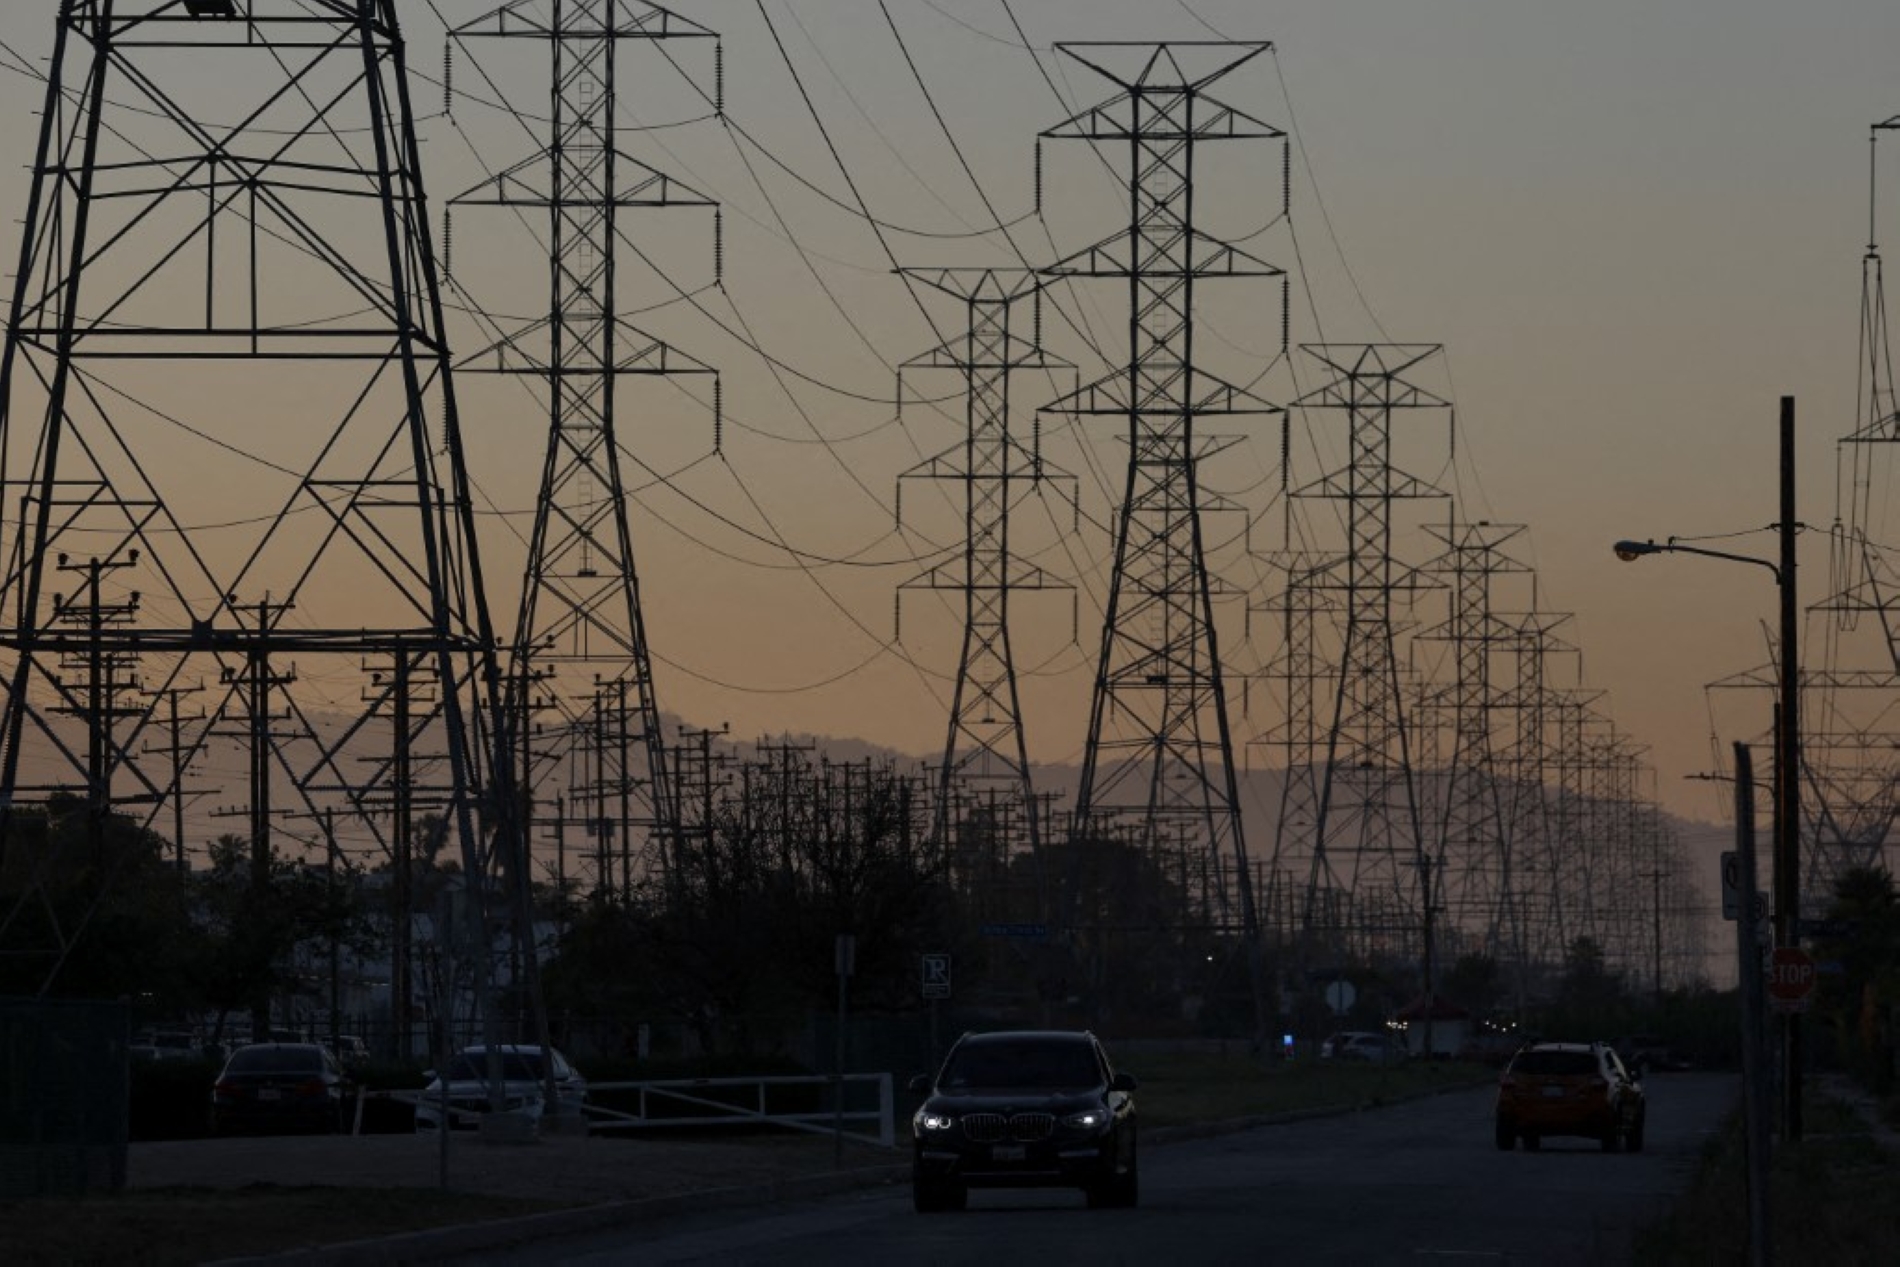
A general view of electrical transmission towers on 25 March 2026, in Los Angeles, California.
The IEA estimates that about 20% of planned data-centre projects could face delays unless grid bottlenecks are addressed. New transmission lines can take between four and eight years to build in advanced economies, while waiting times for transformers and cables have doubled over the past three years.
The pressure appears particularly acute in the United States. In an update published in June 2026, Lawrence Berkeley National Laboratory estimated that US data centres could consume approximately 649 terawatt-hours in 2030 under its reference case, within a range of 521 to 843 terawatt-hours. That would represent between 9.5 and 15.3% of the country's total electricity consumption.
Renewable sources are expected to supply nearly half the global increase in electricity used by data centres through 2035, but natural gas and nuclear power will also play important roles. It is not enough for companies to announce that they have purchased an annual amount of clean energy equivalent to their consumption. They need electricity that is physically available at the site throughout the day, supported by transmission networks, substations and cooling systems capable of handling increasingly dense server installations.
The role of semiconductors
A data centre can be constructed within a country's borders, but its computational heart remains part of a highly concentrated global supply chain. Advanced processor design and manufacturing, lithography equipment, high-bandwidth memory and advanced packaging are distributed among a limited number of companies in the United States, Europe and East Asia.
This creates one of the central paradoxes of the race. A country may possess land, energy and capital, only to discover that its expansion depends on an export decision taken in another capital. Trade restrictions therefore affect more than the price of equipment: they can determine where a data centre is built and whether the project is viable at all.
Under a PwC scenario involving an escalation in US-China restrictions on advanced processors, followed by Chinese controls on certain raw materials, annual global data-centre investment falls to roughly half the central scenario by 2030. It subsequently recovers to some extent as supply chains adjust.
However, the loss is never fully recouped. Cumulative expenditure falls from $31.6tn to $25.5tn, a reduction of about $6tn. The Middle East suffers the largest proportional decline, at 29%, because of its dependence on imported processors and its ambition to attract chip-intensive international AI-training workloads. Asia-Pacific falls from $8.2tn to $6.4tn, while Europe declines from $5.6tn to $4.3tn.
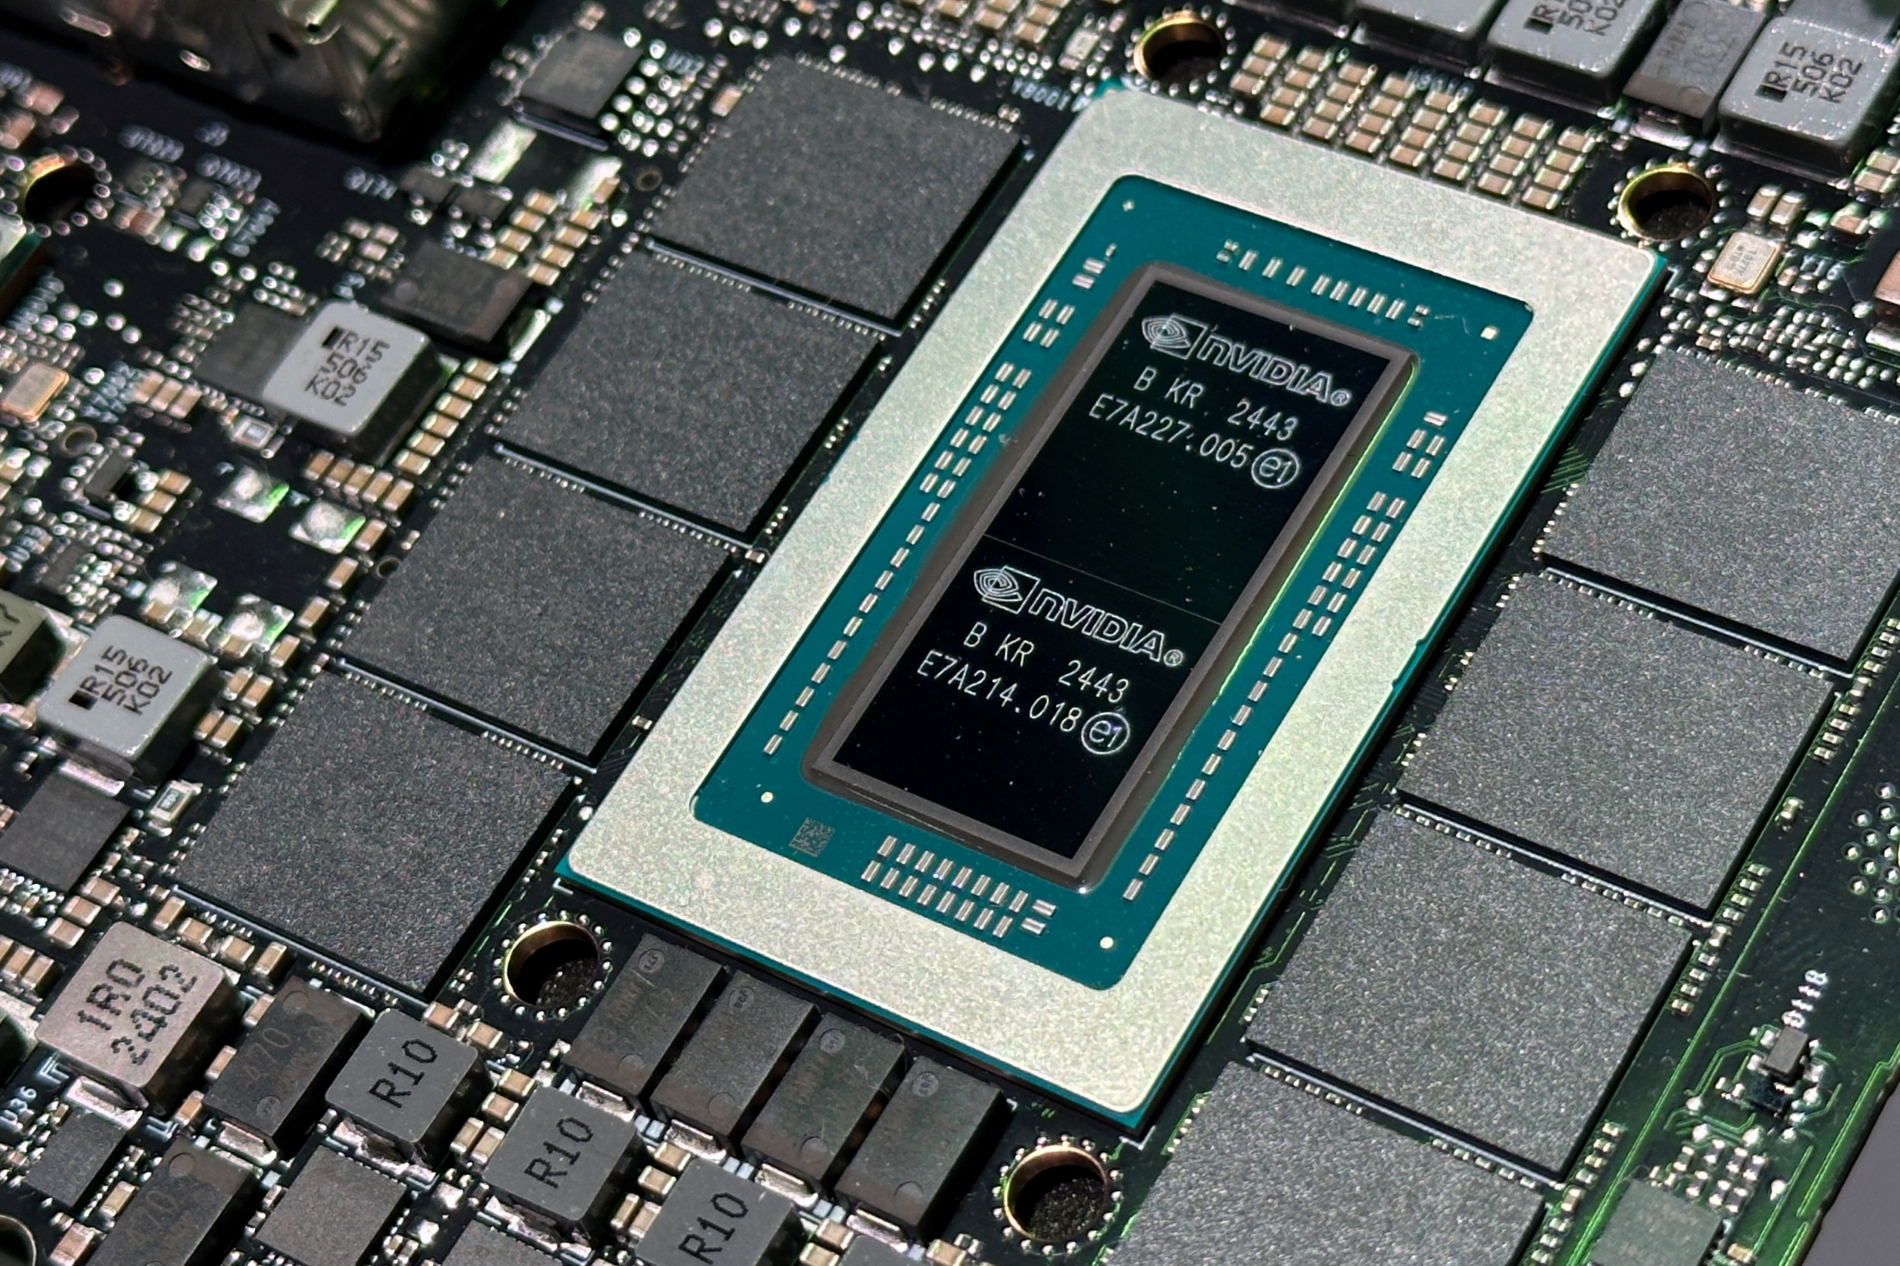
Nvidia GB10 Grace Blackwell Superchip is displayed at the company's GTC conference in San Jose, California, US, on 19 March 2025.
Abundant energy and capital may therefore be insufficient to secure a place in the AI race. Those controlling access to advanced processors effectively gain influence over where the latest computing capacity can be built.
Data exerts pressure in the opposite direction, moving some demand away from large global hubs and towards domestic markets. Training large models does not always need to take place close to the user and can be moved to markets offering cheaper electricity, large sites and better access to processors. Running models on banking, healthcare or government data, however, is more sensitive to privacy, security, latency and sovereignty requirements.
PwC estimates that about 30% of computing workloads already carry local hosting requirements, and that the proportion is rising rapidly. This does not mean that all data-protection laws require domestic storage. European regulations, for example, restrict transfers of personal data abroad and demand legal safeguards, but do not prohibit every transfer. China, meanwhile, requires certain categories of data to be stored domestically by critical information infrastructure operators and organisations exceeding specified thresholds.
Under a scenario in which sovereignty becomes the organising principle, global investment falls by just 6.7%, to $29.5tn, but shifts away from international hubs and towards countries with substantial domestic demand. Asia-Pacific gains 7% and Africa's share rises by about 12%, while the United States loses approximately $2.9tn in workloads that it might otherwise have hosted on behalf of other markets.
The distinction is fundamental: restrictions on semiconductors reduce or delay investment, whereas data sovereignty redistributes it, albeit at the expense of the economies of scale provided by global hubs.
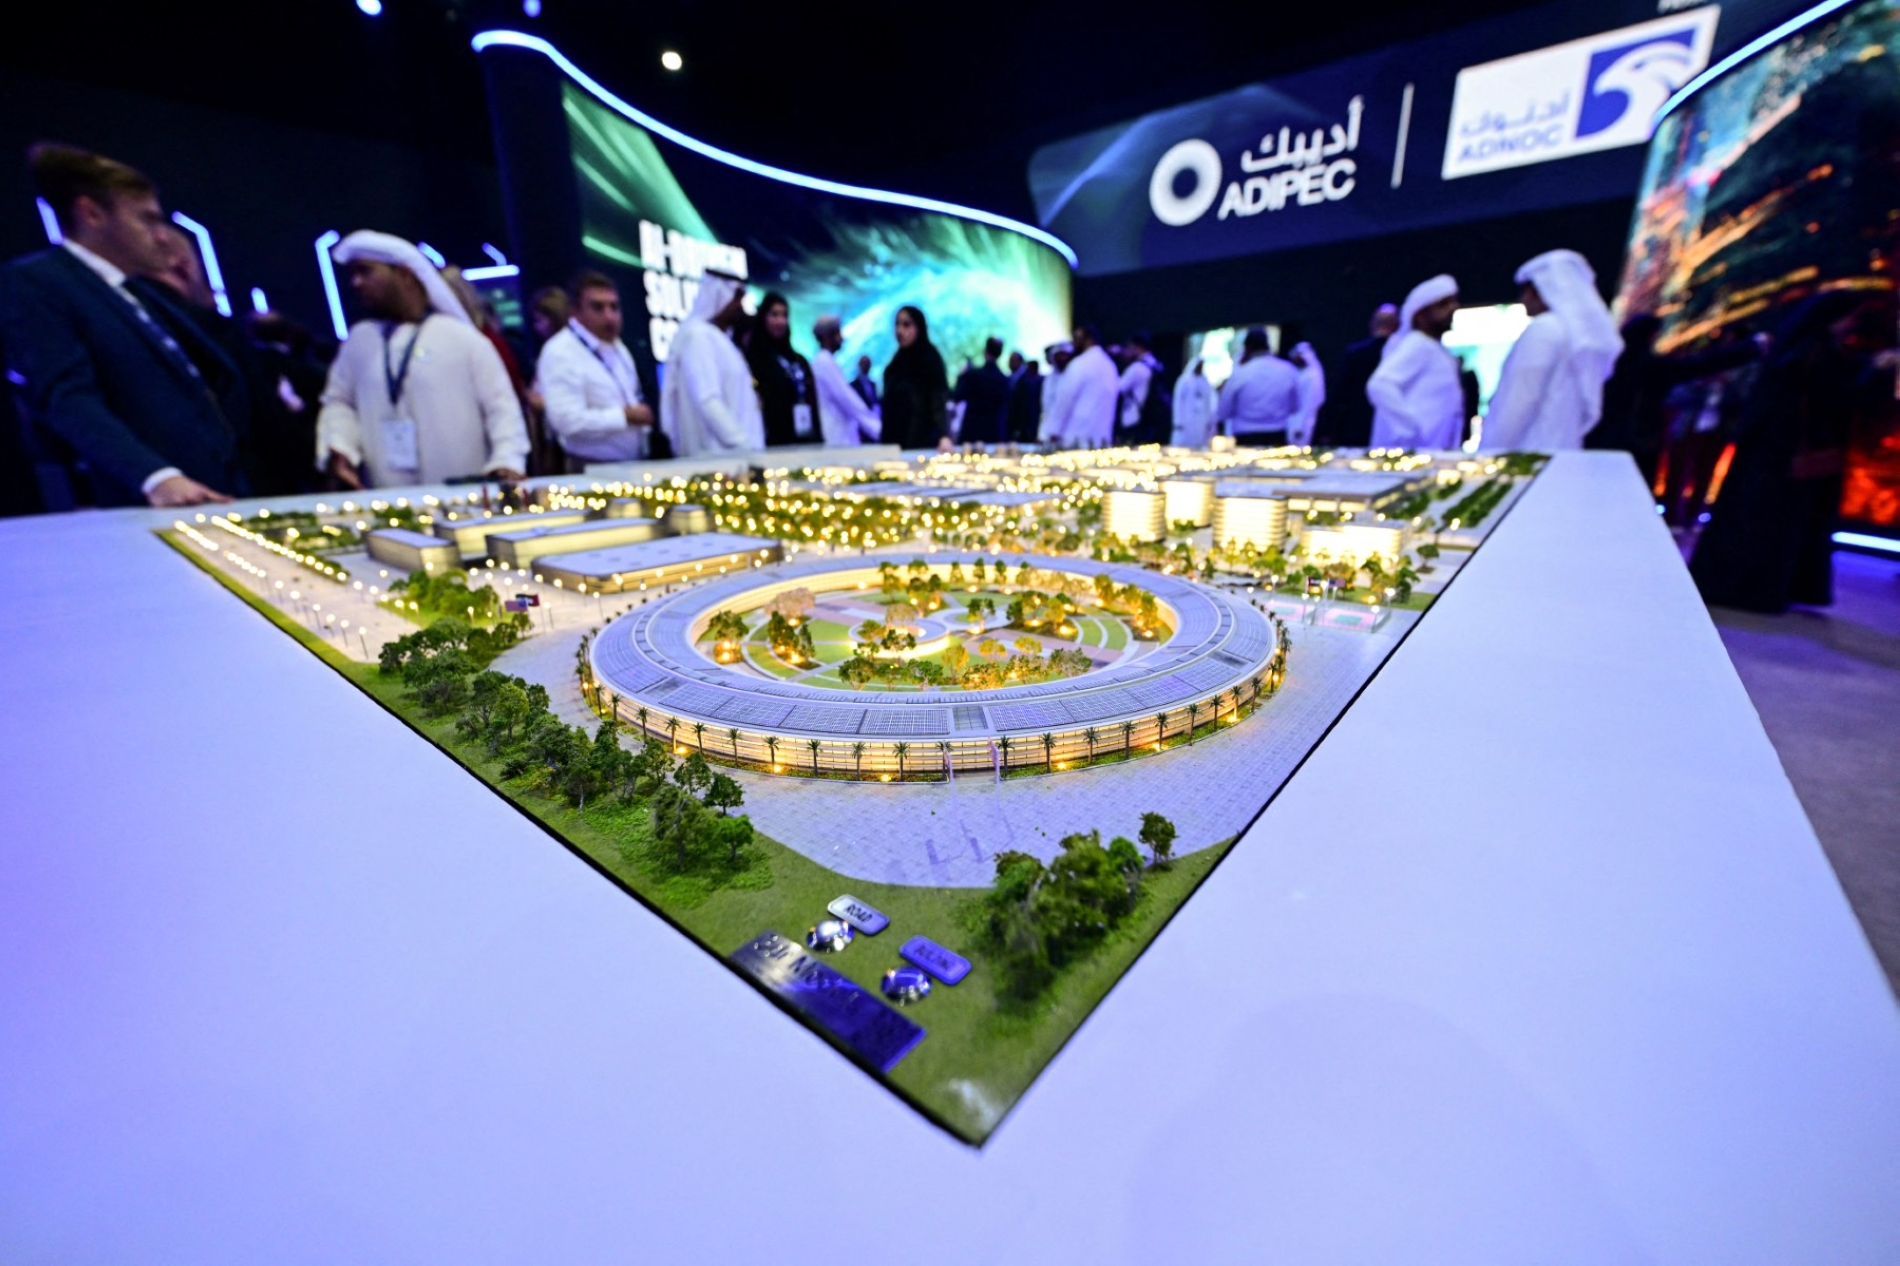
A model of the Stargate initiative, a joint venture between G42, Microsoft, and OpenAI, is displayed in Abu Dhabi on 3 November 2025.
Gulf advantages
The Gulf possesses three advantages that are difficult to combine elsewhere: capital, energy and the ability to accelerate decision-making. Turning them into a lasting position on the global computing map, however, will require more than constructing enormous facilities and announcing their headline capacity.
Each project must secure additional low-carbon electricity, long-term access to processors, contracted customers, a legal environment capable of accommodating sensitive data and a sufficiently skilled local workforce. Returns should also be measured against the consumption of energy, water and land, as well as the incentives provided, rather than by the project's announced value alone.
The Gulf's more durable opportunity may lie in developing a combination of sovereign cloud capacity, Arabic-language inference, and government, banking and healthcare services, rather than relying excessively on attracting internationally mobile model-training operations. Sovereign and regional workloads are more stable and connect data centres to the domestic economy, instead of turning them into stations serving foreign demand that could move elsewhere.